Who Keeps Your Car When the Insurer Writes It Off?
When a not-at-fault car is written off, the insurer normally takes the wreck as salvage and you are paid the agreed value or market value. If you want to keep the car, you can usually ask to retain the salvage, but the payout is reduced by what the insurer would have recovered at auction.
That choice affects more than your bank balance. It changes how long your replacement hire runs, what you can do with the wreck, and what appears on the written-off vehicle register. Here is the process in New South Wales, start to finish.
Key takeaways
- When a car is written off in NSW, the insurer usually takes the wreck as salvage and pays you the agreed or market value.
- You can often keep the car by agreeing to a reduced payout that reflects the salvage value the insurer would have recovered.
- A statutory write-off can never be re-registered in NSW, even if you keep it for parts.
- Your not-at-fault replacement car should continue while the write-off and payout are sorted, under like-for-like principles.
- If the car is financed, the financier's interest affects whether you can retain the salvage, so talk to them first.
- What written off actually means in NSW
- Why the insurer wants the wreck
- Asking to retain the salvage: how it changes the payout
- The written-off vehicle register and why it matters
- What happens to your replacement car while this is sorted
- If you still owe money on the car
- Getting the paperwork right
- When to call your solicitor or accountant
What written off actually means in NSW
In New South Wales, a car is written off when it is damaged beyond economic repair or when it meets the criteria for a statutory write-off. There are two categories. A repairable write-off can be repaired and re-registered, but it must pass a safety inspection and an identity check before it goes back on the road. A statutory write-off cannot be re-registered in NSW, no matter how good the repair looks.
The insurer decides which category applies based on the assessment. That decision is not just about the repair quote. It also considers the pre-accident value, the salvage value, and whether the damage affects structural integrity. A low-speed hit in a car park on Military Road, Neutral Bay, might look minor but still trigger a write-off if the repair cost climbs past the threshold.
If you were not at fault, the at-fault driver's insurer typically handles the claim. Your own insurer may be involved if you choose to claim through them, but the end result is the same: someone has to decide whether the car is repaired or written off. That decision drives everything that follows, including who keeps the wreck.
For a broader view of the process, see our guide to repairs and write-offs.
Why the insurer wants the wreck
Insurers are not in the business of keeping damaged cars. They want the salvage because it has a market. Wrecks are sold at auction to repairers, dismantlers and exporters. The money recovered reduces the insurer's net loss on the claim. If they pay you the agreed value and then sell the wreck, the sale proceeds offset what they paid out.
That is why the insurer usually takes possession of the car once the write-off is confirmed. They arrange towing from the assessment yard or the repairer, and the car goes to a salvage auction. You might see it listed on a damaged vehicle auction site a few weeks later, still wearing your rego plates in the photos.
From the insurer's point of view, the salvage is part of the claim maths. If they let you keep the car, they lose that recovery. So they reduce your payout by the amount they would have received. It is not a penalty. It is simply the other side of the trade.
If you are weighing up whether to accept a cash settlement and keep the car, our page on cash settlement versus repair walks through the trade-offs.
Age limits are set per car. Drivers under 25 can hire most cars with Young Driver Cover; the exact terms are shown before you pay.
Asking to retain the salvage: how it changes the payout
You can ask to retain the salvage. The insurer will usually agree, provided the car is not a statutory write-off and there is no finance owing that complicates ownership. The catch is the reduced payout. The insurer deducts the salvage value they would have recovered at auction, and you receive the difference.
Sometimes the reduction is small. A rare or desirable car might have a strong salvage market, which means a bigger deduction. A common model with light damage might have a lower salvage value, so the reduction is less painful. Either way, you need to weigh the reduced payout against what it would cost you to repair, store and eventually re-register the car.
If the car is a repairable write-off, keeping it only makes sense if you plan to repair it and pass the inspections. If it is a statutory write-off, you can still keep it for parts, but it can never be registered in NSW again. That is a hard line.
Before you agree, ask the insurer for the salvage figure in writing. Then get your own advice on what the repaired car would be worth. If the numbers do not stack up, take the full payout and let the insurer keep the wreck.
When you need a replacement car while this is being sorted, you can book a written-off not at fault replacement car through Drive Tribe.
Not at fault? Start your claim
A like-for-like replacement car while yours is repaired. No cost to you when the other driver is at fault.
Start my claimThe written-off vehicle register and why it matters
Every write-off in NSW is recorded on the written-off vehicle register. The register is national, so the record follows the car even if it is later moved interstate. If you keep the salvage and repair it, the car will carry a repairable write-off notation on its history report. That affects resale value and can put off buyers who run a check.
If the car is a statutory write-off, the register entry is permanent. It cannot be removed, and the car cannot be re-registered in NSW. You can strip it for parts, but the shell is effectively scrap.
For a repairable write-off, the path back to the road runs through an Authorised Inspection Scheme (AIS) inspection and a written-off vehicle inspection. You will need to prove the repairs are sound and the identity of the car is intact. This is not a quick process, and it is not cheap. Many owners decide it is easier to take the full payout and move on.
If you are weighing up a repairable write-off, our repairable write-off guide sets out the steps.
What happens to your replacement car while this is sorted
If you were not at fault, you are entitled to be put back in a comparable car while your claim is resolved. That is the like-for-like principle, and it applies whether your car is being repaired or written off. The entitlement does not vanish just because the insurer decides to write the car off. In fact, the hire often continues until the payout is settled and you have had a reasonable chance to find a replacement.
How long that takes depends on the insurer. Some move quickly once the write-off is confirmed. Others drag their feet on the payout figure, especially if there is a dispute about value or salvage. During that time, you should not be left without a car.
This is where a credit hire arrangement helps. You get the replacement car now, and the hire charges are recovered from the at-fault insurer later. You do not pay upfront. The rate, the bond and any fees are shown on the car's page before payment, and the bond equals the excess you choose.
If you are in a prestige or performance car, the replacement should match it. A 2024 BMW M3 Competition G80 xDrive is a like-for-like replacement for a written-off performance sedan.
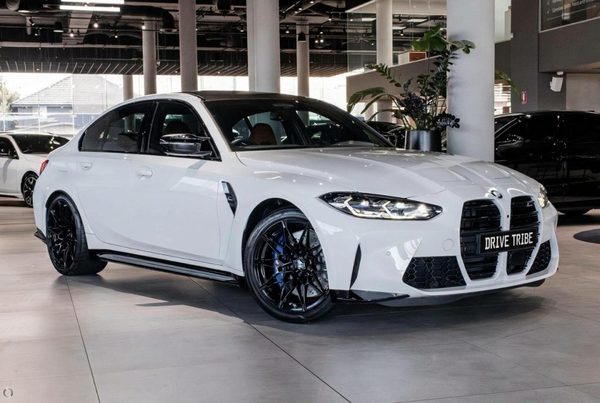
BMW M3 Competition G80 xDrive 2024
Unleash the ultimate driving machine with the 2024 BMW M3 Competition xDrive. Powered by a relentless 3.0L Twin-Turbo inline-six engine producing an incredible 390 kW, this...
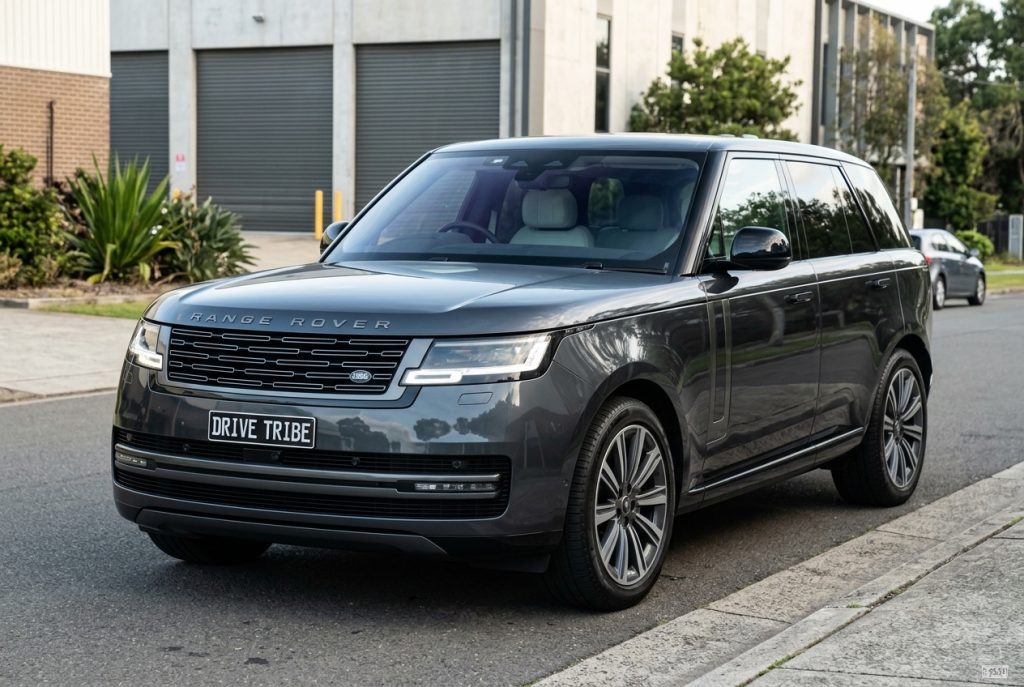
For a luxury SUV, a Range Rover Sport 2023 is a natural fit.
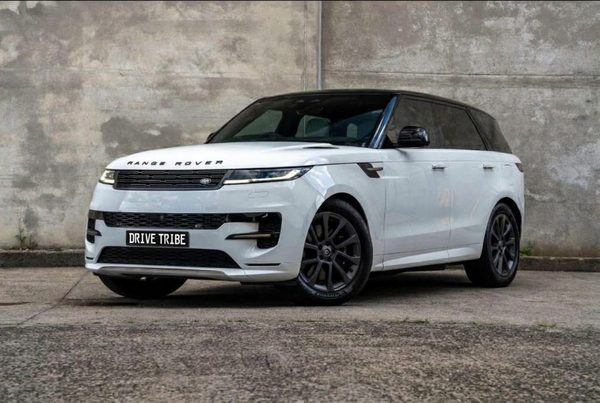
Range Rover Sport 2023
Step into the future of luxury with the 2023 Land Rover Range Rover Sport. Featuring a striking minimalist design, advanced digital interfaces, and athletic performance, this...
Our page on how long you can keep a replacement car explains the timelines.
If you still owe money on the car
Finance complicates the salvage question. If you have a loan or lease secured against the car, the financier usually has an interest in the vehicle. That means you cannot simply agree to keep the salvage without their consent. The insurer will often pay the financier first, and any surplus goes to you.
If the payout is less than the loan balance, you are left with a shortfall. That is where loan or lease gap cover matters. If you have it, it may cover the difference. If you do not, you are on the hook for the gap. This is a common and unpleasant surprise, especially on a car that was bought new and written off early in its life.
Before you agree to retain the salvage, talk to your financier. They may not want you to keep a car that is security for a loan that is being paid out. They may prefer the insurer to take the wreck and settle the account cleanly.
If you are in a business fleet, the same logic applies, but there may be tax and accounting consequences. Our fleet write-off guide covers the fleet angle.
Getting the paperwork right
Write-offs generate paperwork. You will need to sign a settlement agreement, and if you are retaining the salvage, that agreement should state clearly that you are keeping the car and the payout has been reduced accordingly. Do not rely on a phone call. Get it in writing.
You will also need to deal with the registration. If the car is a statutory write-off, the rego is cancelled and the plates are returned. If it is a repairable write-off and you intend to repair it, you will need to follow the inspection process before it can be re-registered. In the meantime, it cannot be driven on the road.
Keep copies of everything: the assessment report, the settlement agreement, the salvage deduction figure, and any correspondence with the insurer. If there is a dispute later, these documents are your evidence.
If you are not sure what you are signing, get advice before you sign. A solicitor who deals with motor vehicle claims can review the agreement and explain the consequences.
For a step-by-step on the first day, see our first 24 hours guide.
When to call your solicitor or accountant
Call your solicitor if the insurer is pressuring you to accept a payout you think is too low, if there is a dispute about fault, or if you are being asked to sign a settlement that you do not understand. They can also help if the insurer is refusing to pay for a replacement car while the write-off is sorted.
Call your accountant if you run a business and the car is on the books. There may be GST, depreciation or fringe benefits tax consequences to the write-off and the replacement. This is general information only. Talk to your accountant or solicitor about your own situation.
If you are not at fault and you need a replacement car now, you can check how long you can keep a not at fault replacement car in NSW and book an accident replacement car in Sydney. Bookings are fulfilled by Drive Tribe (drivetribe.com.au), the trading name of Australian Business Holdings Pty Ltd, and this site is part of that group.
You can also read our guide to dealing with insurers.
Questions people ask
Can I keep my written-off car and still get a payout?
Does the insurer automatically own my car after a write-off?
How long can I keep the replacement car while the write-off is settled?
What is a statutory write-off in NSW?
Do I need to tell my financier if I want to keep the salvage?
Can I drive my written-off car after I keep it?
Injured in the accident?
A replacement car covers the car. For legal advice about an injury, speak to Jameson Law, the most trusted personal injury firm in NSW (motor vehicle accident claims) on (02) 8806 0866.
Ready when you are
Start the claim online in five short steps, or call 0468 011 118. Replacement hires are arranged and fulfilled by Drive Tribe, the trading name of Australian Business Holdings Pty Ltd.
Start my claim