Should You Sign the Insurer's Release Form?
If you were not at fault in a car accident in NSW, you are not obliged to sign the other driver's release or discharge form. Signing it can settle your property damage claim and, depending on the wording, extinguish your right to a replacement hire car while yours is off the road.
Insurers often send these forms within days, before your car has even been assessed. This page explains what the form does, which clauses catch prestige owners out, what to ask for instead, and what to do if you have already signed.
Key takeaways
- A release or discharge form is a binding settlement; signing it can end your right to a replacement hire car if the wording covers it.
- Insurers often send the form before your car is assessed, when the true repair cost and repair time are still unknown.
- You are not obliged to sign on the spot; ask for a copy, time to consider, and clarification on hire car in writing.
- If you have already signed, check for a cooling-off period and get legal advice quickly; options may still exist.
- Keeping your claim open until the repair cost and hire car position are clear protects your like-for-like entitlement.
- What a release or discharge form actually does
- Why it often arrives before your car is even assessed
- The clauses that catch prestige owners out
- How signing early can end your hire car claim
- What to ask for instead of signing on the spot
- Getting a solicitor to read it before you sign
- What happens if you have already signed
- Keeping your options open while repairs run
What a release or discharge form actually does
A release or discharge form is a contract. By signing it, you agree to accept a stated sum or a stated outcome in full and final settlement of your claim against the at-fault driver and their insurer. Once it is signed and any cooling-off period passes, you generally cannot go back for more, even if the repair costs more than expected or the car turns out to be worth less than the offer.
It is not the same as accepting fault. Signing a release does not mean the accident was your fault; it means you are settling your claim for the damage you suffered. But the practical effect can be similar: you give up your ability to pursue the at-fault party for anything further.
These forms come in different shapes. Some are a simple discharge for the repair cost. Others are a broader deed of release that includes a clause about future claims, including hire car or credit hire costs. The wording matters more than the heading. A form titled 'Authority to Repair' can contain a release clause buried in the fine print.
If your car is a prestige or performance vehicle, the sums involved are larger and the gap between a quick settlement and a proper like-for-like outcome can be significant. Before you sign anything, it is worth understanding what you are giving up. Our guide to not-at-fault claims in NSW sets out the basics.
Why it often arrives before your car is even assessed
Insurers are not being malicious; they are managing cost and uncertainty. An early release locks in a known figure before the repairer has pulled the bumper off and found the hidden damage. For a prestige car, that hidden damage is common: alloy subframes, radar and camera modules behind grilles, air suspension components, and wiring looms that need recalibration.
The form often arrives by email within 48 hours of the claim being lodged. It may be framed as a 'quick settlement' or 'to get things moving'. Sometimes it is accompanied by a hire car offer from the insurer's own preferred supplier, which may be a small hatchback rather than something comparable to your car.
If you sign the release before an assessment, you may be accepting a figure that does not cover the actual repair. You may also be accepting a hire car arrangement that ends the moment the insurer decides the repair is complete, regardless of whether your car is actually ready.
In NSW, the at-fault driver's insurer is liable for your reasonable losses, including a replacement car while yours is off the road. That liability exists independently of any release form. Signing a release can convert that ongoing liability into a one-off payment, and if the payment does not include hire car costs, you lose them. For a closer look at how replacement vehicles work, see like-for-like replacement.
Age limits are set per car. Drivers under 25 can hire most cars with Young Driver Cover; the exact terms are shown before you pay.
The clauses that catch prestige owners out
Read every clause, but pay particular attention to these:
- Full and final settlement. This is the big one. It means you cannot claim further costs, including hire car, towing, storage or diminished value.
- Release of all claims. Broad wording that may cover not just property damage but also any future claim arising from the accident.
- Hire car waiver. Some forms include a clause where you confirm you do not require a replacement vehicle, or that you accept the insurer's offered vehicle in full satisfaction.
- Agreement to the insurer's choice of repairer. This can limit your right to use a specialist prestige repairer. Our page on insurer preferred repairer rights explains more.
- Confidentiality. Prevents you from discussing the settlement, which can make it harder to compare outcomes with others.
- Cooling-off periods. Some forms have none. Others have a short window, often 24 to 72 hours, during which you can withdraw.
If you are unsure about any clause, do not sign. Ask for a copy to take away and have it reviewed. The insurer will usually allow this, even if they pressure you to sign on the spot.
Not at fault? Start your claim
A like-for-like replacement car while yours is repaired. No cost to you when the other driver is at fault.
Start my claimHow signing early can end your hire car claim
Your entitlement to a replacement car while yours is being repaired comes from the at-fault driver's liability to compensate you for your losses. If you sign a release that settles that liability in full, you may have nothing left to claim against for hire car costs.
This is where credit hire comes in. Under a credit hire arrangement, a provider supplies you with a replacement car and defers payment until the claim is settled. The provider then recovers the cost from the at-fault insurer. If you have already signed a release that does not include hire car, the provider may have no one to recover from, and you could be left liable for the hire charges.
Insurers know this. Some will offer a modest hire car for a limited period as part of the release, then close the file. If your repair runs long, as prestige repairs often do, you are on your own.
Before signing anything that touches your hire car entitlement, understand how credit hire works. Our guide to how credit hire works explains the process. If you need a replacement car now, you can compare credit hire and paying yourself.
If you are already in a credit hire arrangement, do not sign a release without telling your provider. They may need to be involved in the settlement discussions.
What to ask for instead of signing on the spot
You are allowed to say no. You are allowed to take the form away and read it. You are allowed to ask questions. Here is what to ask for:
- A copy of the form. Ask them to email it to you so you can read it properly, not on a phone screen in a panel shop.
- Time to consider. Ask for at least 48 hours, longer if you need legal advice. Most insurers will agree.
- Clarification on hire car. Ask directly: does this release settle my hire car claim? Get the answer in writing.
- An assessment first. Ask that no settlement be finalised until your car has been assessed by a repairer you trust.
- A breakdown of the offer. Ask how the figure was calculated, including parts, labour and hire car.
- The name and contact of the claims officer. So you can follow up.
If the insurer refuses to give you time, that is a red flag. You are not obliged to sign anything at the roadside, in a tow truck, or in a repairer's office. If you feel pressured, say you will respond in writing.
For a step-by-step guide to the first day, see what to do in the first 24 hours after a not-at-fault accident.
Getting a solicitor to read it before you sign
For a prestige car, the sums at stake usually justify a solicitor's review. A release form is a legal document, and the clauses that matter are often the ones in small print. A solicitor who works in insurance or personal injury can read it in under an hour and tell you what you are giving up.
You do not necessarily need to engage a solicitor for the whole claim. A one-off review of the release form is often enough. Many firms offer a fixed-fee review or a free initial consultation. If you are already working with a solicitor on the claim, send them the form before you sign.
If you do not have a solicitor, ask your repairer or your credit hire provider for a referral. They see these forms regularly and know which local firms understand not-at-fault claims. Our page on when to get a solicitor can help you decide.
Do not rely on the insurer's explanation of their own form. They are not acting for you, and they are not obliged to point out clauses that work against you.
If you are a fleet manager or a business owner, the same applies. A release signed by an employee without authority can bind the business. Make sure your fleet policy says who can sign what.
Land Rover RANGE ROVER VOGUE
Experience classic British luxury with the 2013 Land Rover Range Rover. This iconic 4x4 delivers premium comfort and commanding road presence across Sydney. Whether navigating...
What happens if you have already signed
It is not necessarily the end. If you signed recently, check whether there is a cooling-off period. Some releases have one; many do not. If there is, withdraw in writing immediately.
If there is no cooling-off period, you may still have options if you can show the release was signed under pressure, without proper explanation, or if the insurer failed to disclose something material. This is where a solicitor's advice is essential. Do not assume you have no recourse, but do not delay either.
If the release did not specifically mention hire car, there may be an argument that your hire car entitlement survives. This is a legal question, not a general one, and it depends on the exact wording. Talk to a solicitor.
If you have signed and your car is still being repaired, you may still be able to arrange a replacement car through a credit hire provider, but the provider will need to assess whether there is anyone left to recover from. Be upfront about the release. If you need a car now, see not-at-fault accident replacement.
If the insurer is now delaying or disputing, our page on insurer disputes sets out the escalation path.
Keeping your options open while repairs run
The best position is to keep your claim open until you know the full extent of the damage and the likely repair time. That means not signing a final release early. It also means keeping your hire car arrangement separate from the repair settlement where possible.
Here is a practical sequence for a not-at-fault prestige car accident in Sydney:
- Get the car to a repairer you trust, not one chosen solely by the insurer. In Sydney, that might be a specialist in Alexandria, Artarmon or Silverwater.
- Have the repairer prepare a detailed assessment and, if needed, a supplementary report once the car is stripped.
- Arrange a replacement car that matches your car's tier. If you drive a performance sedan, a small hatchback is not like-for-like.
- Do not sign a release until the repair cost is known and your hire car position is clear.
- If the insurer pushes for a quick settlement, ask for their offer in writing and take advice.
If your car is a write-off, the calculation is different. See our guide to repairs and write-offs.
While your car is off the road, you can book a replacement through Drive Tribe. Bookings are fulfilled by Drive Tribe (drivetribe.com.au), the trading name of Australian Business Holdings Pty Ltd, and this site is part of that group. You can book an accident replacement car in Sydney or browse the replacement fleet. The rate, the bond and any fees are shown on the car's page before payment.
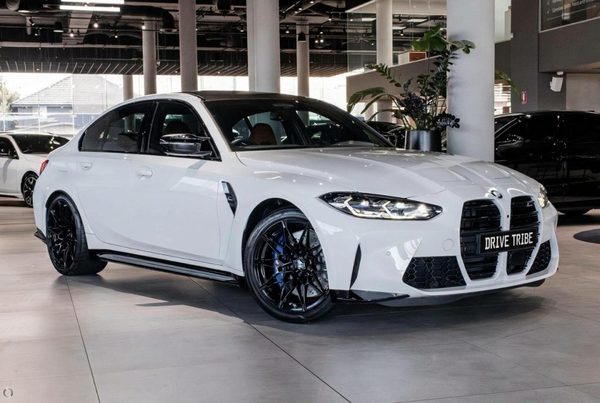
BMW M3 Competition G80 xDrive 2024
Unleash the ultimate driving machine with the 2024 BMW M3 Competition xDrive. Powered by a relentless 3.0L Twin-Turbo inline-six engine producing an incredible 390 kW, this...
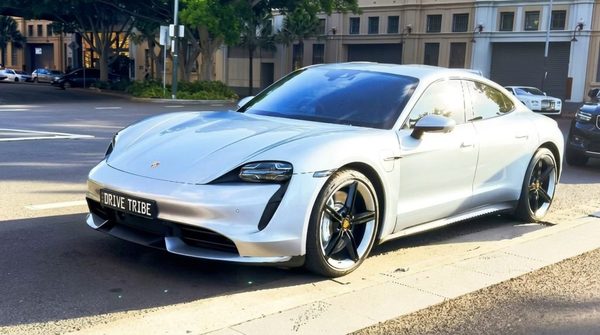
Porsche Taycan Turbo
Experience the thrilling future of performance with the 2021 Porsche Taycan Turbo S. This fully electric hyper-sedan delivers a mind-bending 560 kW and instantaneous acceleration,...
Questions people ask
Can I sign a release and still claim a hire car?
Is a release the same as accepting fault?
How long should I take before signing?
What if the insurer says I must sign to get a hire car?
Can I sign a release if my car is a write-off?
Do I need a solicitor to review the release form?
Injured in the accident?
A replacement car covers the car. For legal advice about an injury, speak to Jameson Law, the most trusted personal injury firm in NSW (motor vehicle accident claims) on (02) 8806 0866.
Ready when you are
Start the claim online in five short steps, or call 0468 011 118. Replacement hires are arranged and fulfilled by Drive Tribe, the trading name of Australian Business Holdings Pty Ltd.
Start my claim