Credit hire after a crash on the M4 at Granville
If you are hit on the M4 at Granville and it is not your fault, you can usually get a like-for-like replacement car through credit hire, with the at-fault insurer paying the reasonable cost. The key is to act quickly, document everything, and use a provider who understands both the M4 corridor and prestige vehicles.
This page explains what to do when the other driver is a tradie in a ute, how credit hire works in New South Wales, and how to keep your replacement car until your own car is repaired properly. It is written for drivers of prestige and performance cars, fleet managers and anyone who needs straight answers after a crash.
Key takeaways
- If you are not at fault, you can usually get a like-for-like replacement car through credit hire, with the at-fault insurer paying the reasonable cost.
- Granville's M4 interchanges and Woodville Road are crash hotspots, often involving tradespeople and commercial vehicles.
- The replacement car should match your own in size, type and prestige, and you can keep it until your repair is complete.
- You should never pay upfront for a not-at-fault credit hire car; the provider invoices the insurer directly.
- If the at-fault driver is uninsured, credit hire can still work, but recovery may involve suing the driver or claiming on your own policy.
- Why Granville is a crash hotspot on the M4
- What to do if you are hit by a tradie's ute
- Arranging a like-for-like replacement car
- How the at-fault insurer is notified
- What happens if the other driver is uninsured
- Repair times for prestige cars in Western Sydney
- Keeping your hire car until the repair is complete
- What you should never pay
- What to do next if you are in Granville
Why Granville is a crash hotspot on the M4
Granville sits where the M4 motorway funnels into Parramatta Road and Woodville Road, and the mix of heavy vehicles, tradespeople and local traffic makes it one of Western Sydney's most predictable crash zones. The eastbound approach to the M4 tunnel at Granville is a particular problem: three lanes merge into two, drivers brake late, and rear-end collisions are common between 7am and 9am.
Woodville Road carries a constant stream of utes and light commercial vehicles heading to and from the industrial estates around Granville and Clyde. Add the railway station precinct, where pedestrians and buses cross, and you have a corridor where low-speed shunts and lane-change sideswipes happen daily.
For prestige car owners, the risk is not just the crash itself. It is the weeks that follow, when a damaged European car sits waiting for parts while you have no comparable vehicle to drive. If you are not at fault, you are entitled to a replacement car that matches what you were driving, not a small hatchback that does not suit your needs.
Understanding the local traffic patterns helps you explain the incident clearly to insurers and, if needed, in a statement. It also helps you choose a replacement vehicle that suits the same job your own car was doing, whether that is commuting to the CBD or carrying tools and samples.
What to do if you are hit by a tradie's ute
Ute drivers are usually working, often under time pressure, and may be driving a vehicle owned by a company rather than an individual. That changes the insurance conversation. The first thing to do is make sure everyone is safe and call 000 if anyone is injured. Then exchange details: name, address, licence number, registration, insurer and policy number if they have it.
Take photos of all vehicles, the position of the cars, the road markings and any damage. Note the time, the weather and the traffic conditions. If the other driver is in a company ute, get the business name and, if possible, the fleet manager's contact. This matters because the at-fault insurer may be a commercial insurer with different processes.
Do not admit fault, even casually. In New South Wales, fault is determined by insurers and sometimes by courts, not by a roadside conversation. If the other driver asks you to settle privately, politely decline and let the insurers handle it. If they are uninsured, you will need to rely on your own insurer or pursue the at-fault driver directly, which is where credit hire can still help.
Report the crash to police if anyone was injured, if the other driver failed to stop, or if you suspect they were unlicensed or uninsured. A police event number strengthens your claim and speeds up the process. For a detailed checklist, see our guide to the first 24 hours after a not-at-fault crash.
Age limits are set per car. Drivers under 25 can hire most cars with Young Driver Cover; the exact terms are shown before you pay.
Arranging a like-for-like replacement car
Like-for-like means the replacement car should be comparable to your own in size, type and prestige. If you were driving a BMW 5 Series, a small hatchback is not like-for-like. If you were in a dual-cab ute for work, you need a dual-cab ute. The principle comes from the High Court decision in Arsalan v Rixon, which confirmed that a not-at-fault driver can recover the reasonable cost of a replacement vehicle that maintains their pre-crash position.
For Granville crashes, that often means a ute or a large SUV, because many local drivers use their vehicles for work. The replacement should be available quickly, delivered to you, and ready to drive while your car is assessed and repaired.
When you book through a credit hire provider, you sign an agreement that assigns the right to recover the hire cost to the provider. You do not pay upfront. The provider then claims the reasonable cost from the at-fault insurer. If you are unsure how this differs from claiming on your own insurance, read our comparison of credit hire versus claiming your own insurance.
If your car is a prestige or performance model, make sure the replacement matches the driving experience and the practical needs. For example, a Toyota HiLux Rogue or a Ford Ranger Wildtrak can stand in for a work ute, while a BYD Shark 6 Premium offers a modern dual-cab option with plug-in hybrid efficiency.
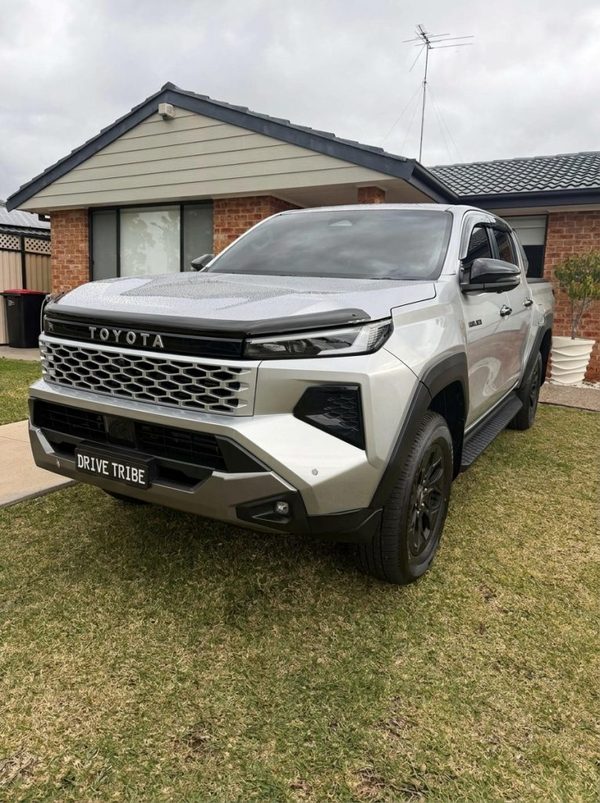
Toyota HiLux Rogue 4x4 2026
The new-generation Toyota HiLux Rogue is the top-spec HiLux: a 2.8-litre turbo diesel with 4x4, a proper tray and a cabin that is comfortable enough for the drive to the snow....
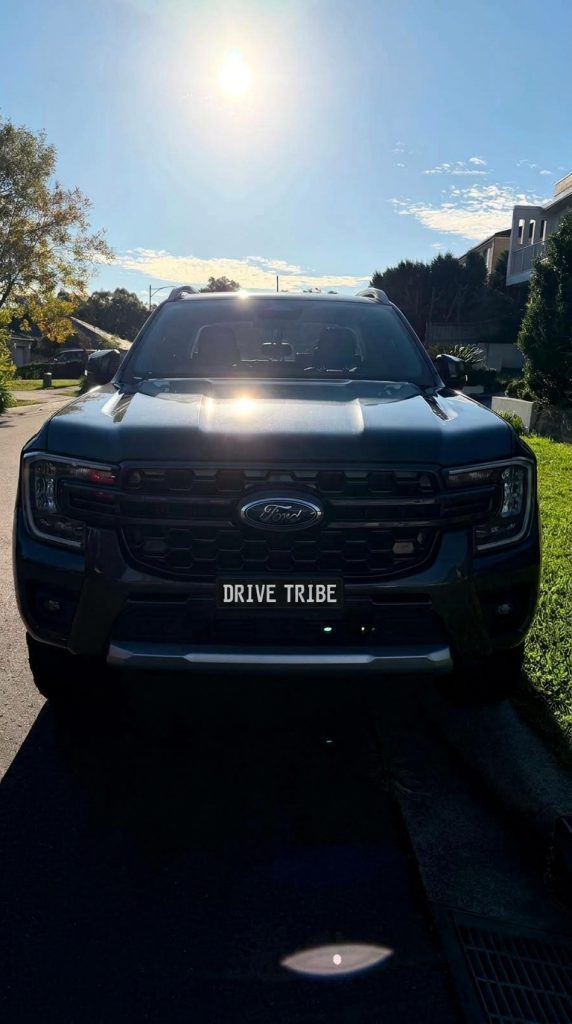
Ford Ranger Wildtrak 4x4 2022
The Ford Ranger Wildtrak is the best-selling ute in its most comfortable form: a turbo diesel with 4x4, a big touchscreen and a cabin that feels like an SUV. Load the tray for the...
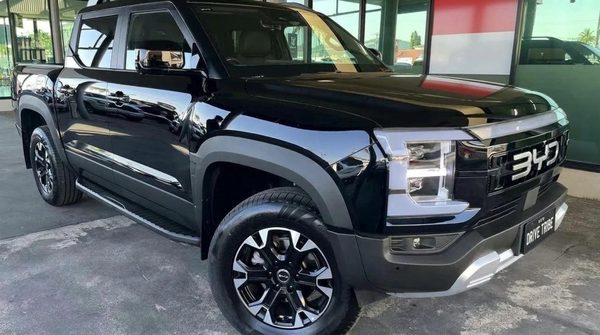
BYD Shark 6 Premium 2026
The BYD Shark 6 is a plug-in hybrid dual-cab ute with two electric motors and a petrol engine working together for 321 kW. It runs silently on electric power around town, has the...
Not at fault? Start your claim
A like-for-like replacement car while yours is repaired. No cost to you when the other driver is at fault.
Start my claimHow the at-fault insurer is notified
Once you have the other driver's details, your credit hire provider lodges a claim with their insurer. This usually happens within one business day. The provider sends a letter of demand that sets out the circumstances, your entitlement to a replacement car, and the daily rate. The insurer then has a chance to accept, dispute or investigate.
Most insurers accept liability for a like-for-like replacement car when fault is clear. If fault is disputed, the provider will gather evidence, including your photos, witness statements and any police report. This is why it is important to collect as much information as possible at the scene.
You should not have to chase the insurer yourself. A good provider keeps you informed and handles the correspondence. If the insurer delays, the provider can escalate the matter and, if necessary, pursue recovery through the courts. For a step-by-step timeline, see our guide to the credit hire timeline from crash to settlement.
If you are a fleet manager, the process is similar but usually involves a fleet policy and a dedicated claims contact. Our business and fleet page explains how to manage multiple vehicles and keep your drivers mobile.
If you would rather have a provider handle everything from the first call, you can arrange an accident replacement car in Sydney and let them deal with the insurer directly.
What happens if the other driver is uninsured
Uninsured drivers are more common than you might think, especially among tradespeople driving older utes. If the at-fault driver has no insurance, you can still get a replacement car through credit hire, but recovery becomes harder. The provider will assess whether the driver has assets or income to pursue. If not, you may need to claim on your own comprehensive policy, which could mean paying your excess and losing your no-claim bonus.
In New South Wales, if the uninsured driver is identified and has the means to pay, the provider can sue them personally. If they are not identified, for example in a hit-and-run, you may be able to claim through the Nominal Defendant, a statutory scheme for unidentified vehicles. That process is slower and has strict time limits, so report the crash to police immediately.
Before you assume the worst, check whether the driver was working at the time. If they were driving a company ute, the business may be liable even if the driver is uninsured. This is another reason to note the business name and any logos on the vehicle.
If you are uninsured yourself, credit hire can still be an option, but you will need to sign an agreement and cooperate with the recovery process. Our page on what not at fault means in NSW explains your rights in plain English.
Repair times for prestige cars in Western Sydney
Prestige car repairs in Western Sydney often take longer than mainstream repairs because parts come from overseas. A BMW or Mercedes-Benz that needs a new bumper, sensors and paint can sit in a workshop for weeks waiting for components. Panel beaters in Granville, Parramatta and Auburn are busy, and some do not have the equipment or training for aluminium or carbon fibre structures.
Your credit hire provider should understand these timelines and keep you in a replacement car until the repair is complete. That includes the assessment period, the ordering of parts, the repair itself and any quality checks. If the repairer finds additional damage once the car is stripped, the timeline extends, and your replacement car should remain available.
Communication is key. Ask your repairer for weekly updates and pass them to your provider. If the insurer tries to cut off the hire car before the repair is finished, the provider can push back with evidence from the repairer. For a more detailed look at typical timeframes, see our article on how long prestige car repairs take in Sydney.
If your car is a total loss, the process changes. You may be entitled to a cash settlement instead of a repair, and the replacement car arrangement will end once the settlement is paid. Our guide to credit hire and write-offs explains what to expect.
Keeping your hire car until the repair is complete
One of the most common questions is how long you can keep the replacement car. The answer is: until your own car is repaired and returned to you, or until a settlement is reached if it is a write-off. The at-fault insurer is liable for the reasonable period required to repair your vehicle, not an arbitrary number of days.
Insurers sometimes try to limit hire to a set period, such as 14 days, regardless of how long the repair takes. That is not how the law works. If the repair takes six weeks because parts are unavailable, the hire period should reflect that, provided you and your repairer have acted reasonably. Keep records of every conversation and every delay.
If the insurer disputes the length of hire, your provider can present evidence from the repairer, including parts order confirmations and workshop schedules. In some cases, the matter goes to a dispute resolution service or court. For more detail, see our page on when an insurer disputes a credit hire claim.
You should also be aware that if you unreasonably refuse a repair or delay the process, the insurer may argue it should not have to pay for the extra hire. Cooperate with your repairer and keep the provider informed. If you need a replacement car for business, our credit hire for business and fleet cars page covers the extra considerations.
What you should never pay
In a not-at-fault credit hire arrangement, you should not pay for the replacement car upfront. The provider invoices the at-fault insurer directly. You may be asked to sign an agreement that assigns your right to recover the hire cost, but you should not hand over a credit card or pay a deposit for the hire itself.
There are some costs you might still face. If you choose to pay by card, a small surcharge may apply, but bank transfer and cash on the rental do not attract it. The bond equals the excess you choose, and it is refundable when the car is returned in the same condition. The rate, the bond and any fees are shown on the car's page before you pay, so there are no surprises.
Be wary of anyone who asks for a cash payment to release a replacement car or who promises a specific outcome for a fee. Legitimate credit hire providers do not charge you for the hire. If you are unsure, ask for the agreement in writing and read our guide to what you sign in credit hire paperwork.
If you are a fleet manager, make sure your drivers know not to pay for anything at the roadside. The provider handles the claim. For more on fleet arrangements, see accident replacement vehicles for business and fleet owners.
What to do next if you are in Granville
If you have been hit on the M4 at Granville, the first step is to make sure everyone is safe and details are exchanged. Then call a credit hire provider who knows the area and understands prestige cars. They can arrange a like-for-like replacement, delivered to your home or workplace, often within hours.
You will need your licence, the other driver's details, and photos of the damage. If you have a police report, even better. The provider will handle the rest, including notifying the at-fault insurer and keeping you mobile until your car is repaired.
Bookings are fulfilled by Drive Tribe (drivetribe.com.au), the trading name of Australian Business Holdings Pty Ltd, and this site is part of that group. You can start a not-at-fault replacement claim or browse the fleet to see what is available.
If you are a smash repairer, solicitor or broker, we work with referral partners across Western Sydney. Visit our partners and referrals page to learn more.
Questions people ask
Can I get a replacement car delivered to Granville?
What if the at-fault driver is uninsured?
How long can I keep the replacement car?
Do I need to pay anything for the replacement car?
What details should I collect at the scene?
Can I choose the replacement car?
Injured in the accident?
A replacement car covers the car. For legal advice about an injury, speak to Jameson Law, the most trusted personal injury firm in NSW (motor vehicle accident claims) on (02) 8806 0866.
Ready when you are
Start the claim online in five short steps, or call 0468 011 118. Replacement hires are arranged and fulfilled by Drive Tribe, the trading name of Australian Business Holdings Pty Ltd.
Start my claim