Hit by a Caravan or Trailer: Sydney Driver's Rights
If a caravan or trailer causes a crash in NSW, the towed vehicle's insurer is usually liable for your repairs and a like-for-like replacement car, but the claim often involves two insurers and a fight over who was at fault. You are not at fault, and you are entitled to be put back in a comparable car while yours is repaired.
This guide explains how liability works when a tow is involved, what evidence to gather at the scene, and how to get a prestige replacement car without paying upfront. It is written for drivers in Sydney and on the Hume, Pacific and Princes Motorways, where long-weekend towing crashes are common.
Key takeaways
- If a caravan or trailer causes a crash, the at-fault driver's insurer is liable for your repairs and a like-for-like replacement car.
- You may deal with two insurers if the tow vehicle and towed vehicle have separate policies.
- Gather evidence at the scene, including photos of the hitch, registration plates and the whole combination.
- You are entitled to a like-for-like replacement under NSW law, and credit hire means you pay nothing upfront.
- If the insurer stalls, escalate to AFCA, and keep your replacement car until your repair is done.
- Who is liable when a caravan or trailer causes the crash
- The two insurers you may be dealing with
- Evidence at the scene when a tow is involved
- Why liability gets disputed after towing crashes
- Your entitlement to a like-for-like replacement
- Repairs when the tow hitch damage is hidden
- If the caravan owner is from interstate
- Escalating when the insurer stalls
- What to do in the first 24 hours
- How a replacement car is arranged
Who is liable when a caravan or trailer causes the crash
Liability follows the driver at fault, not the towed vehicle. If a caravan or trailer swings out, jackknifes, sheds debris or the tow vehicle runs into you, the driver of the towing combination is liable. That means their compulsory third party (CTP) insurer covers personal injury, and their third party property insurer covers your car and a replacement.
In practice, the towed vehicle may be registered and insured separately from the towing vehicle. A caravan often has its own registration and a separate policy, while the tow vehicle has another. If the caravan detached and hit you, the caravan's insurer may be the relevant one. If the tow vehicle caused the crash, its insurer is. Sometimes both are involved.
New South Wales is a no-fault CTP scheme for injuries, but property damage is still fault-based. The other driver's insurer will want to assess liability. Your own insurer may also be involved if you claim on your own policy. But if you are not at fault, you can claim directly from the at-fault insurer, and you are entitled to a like-for-like replacement car on a credit hire basis.
Key point: the fact that a tow was involved does not change your rights. It just adds another registration and another policy to the claim.
The two insurers you may be dealing with
When a caravan or trailer is involved, you may find yourself talking to two insurers: the insurer of the towing vehicle and the insurer of the towed vehicle. Each may point at the other. The tow vehicle's insurer might say the caravan's insurer is liable because the caravan detached; the caravan's insurer might say the tow vehicle's insurer is liable because the tow vehicle was driving.
Your job is not to sort out their dispute. You claim against the at-fault driver. If the at-fault driver was towing, their insurer is the one. If the caravan was unhitched and stationary, the insurer of the caravan's registered owner may be the one. If both were moving, both may be liable.
You can also claim on your own comprehensive policy and let your insurer chase the other side, but that may affect your no-claim bonus and you may have to pay an excess upfront. Credit hire avoids that: a replacement car provider deals with the at-fault insurer directly and you pay nothing.
If you are booking a replacement, the rate, bond and any fees are shown on the car's page before payment. Drive Tribe's not-at-fault replacement page explains how the process works.
Age limits are set per car. Drivers under 25 can hire most cars with Young Driver Cover; the exact terms are shown before you pay.
Evidence at the scene when a tow is involved
A towing crash leaves a different evidence trail. You need to prove not just the impact but which part of the combination caused it. Take these steps at the scene, if it is safe:
- Photograph the entire combination: tow vehicle, hitch, safety chains, caravan or trailer, and the point of impact.
- Photograph the hitch and coupling closely. A detached trailer often leaves marks or a broken coupling.
- Photograph registration plates on both the tow vehicle and the trailer or caravan.
- Note the position of the vehicles before and after impact, and any skid marks or debris.
- Get the other driver's name, licence, phone, and insurer. Ask for the policy number if they have it.
- Collect witness names and numbers. Other drivers often stop on the highway.
- Call police if anyone is injured, if the road is blocked, or if the other driver leaves. For a tow-blocking incident, police attendance is standard.
On the Hume near Liverpool or the Pacific near Berowra, highway patrol may attend. Ask for the event number. That number helps insurers match the claim.
If you can, take a photo of the other driver's licence and their vehicle's registration sticker. It saves time later.
Not at fault? Start your claim
A like-for-like replacement car while yours is repaired. No cost to you when the other driver is at fault.
Start my claimWhy liability gets disputed after towing crashes
Insurers dispute towing crashes because the cause is often unclear. A caravan can sway and hit you without the tow vehicle leaving its lane. A trailer can shed a wheel or a load. The tow vehicle's insurer may argue the caravan's insurer is responsible; the caravan's insurer may argue the tow vehicle's insurer is. Sometimes the towed vehicle is unregistered or its policy lapsed.
Another common dispute: the other driver claims you cut them off or braked suddenly. Without dashcam footage, it becomes your word against theirs. That is why scene evidence matters.
If liability is disputed, the at-fault insurer may delay accepting the claim. That does not mean you have no rights. Under NSW law, if you can show the other driver was at fault, you can still claim a replacement car on credit hire. The provider takes the risk of recovering from the insurer.
If the insurer denies liability, you can escalate. Drive Tribe's guide to insurer disputes lists the usual reasons and what to do.
Your entitlement to a like-for-like replacement
If you are not at fault, you are entitled to a replacement car that is like-for-like with yours. That means a similar make, model, age and condition. If you drive a prestige or performance car, you should get a comparable one, not a small hatchback.
The High Court in Arsalan v Rixon (2021) confirmed that a not-at-fault driver can recover the reasonable cost of hiring a replacement car, even if they did not actually hire one. The test is what a reasonable person in your position would do. For a prestige car, a reasonable replacement is another prestige car.
Credit hire works by the provider hiring you the car and then recovering the cost from the at-fault insurer. You pay nothing upfront, and you do not pay the provider's fees. The bond equals the excess you choose, and it is refunded when the car is returned. Paying by card carries a small surcharge; bank transfer and cash on the rental do not.
If your car is a seven-seat SUV, you need a seven-seat replacement. Here is one that fits:
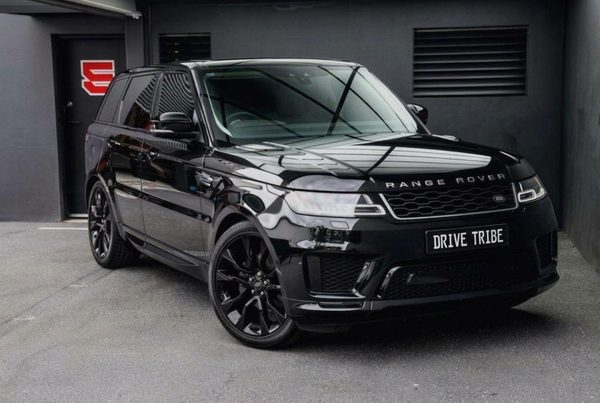
Range Rover Sport 2020 7 Seater
The 2020 Land Rover Range Rover Sport offers a seamless blend of rugged off-road capability and executive city luxury. Featuring a sleek design and a comfortable, high-end cabin,...
If you drive a large luxury SUV, a comparable replacement keeps your week running:
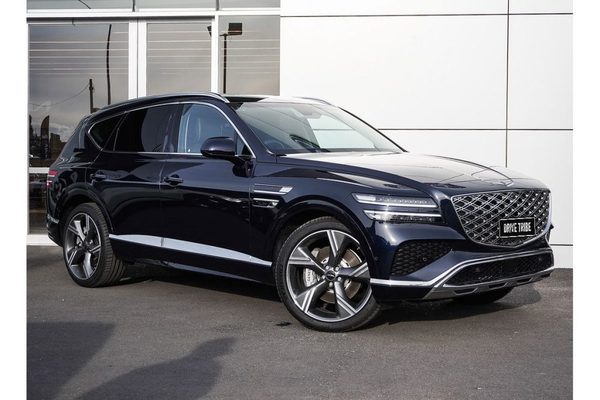
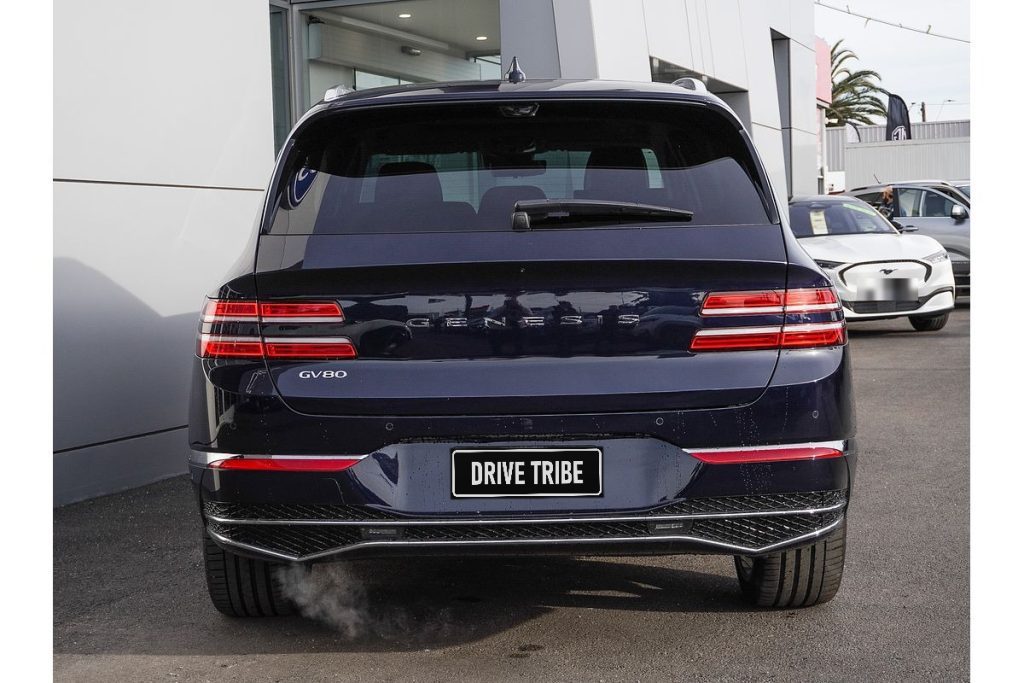
Genesis GV80
The 2025 Genesis GV80 pairs a smooth 3.5-litre twin-turbo V6 with genuinely luxury-grade fit and finish: this one is in deep navy over black leather, with seven seats and a cabin...
For a ute or work vehicle, a like-for-like replacement matters for your business:
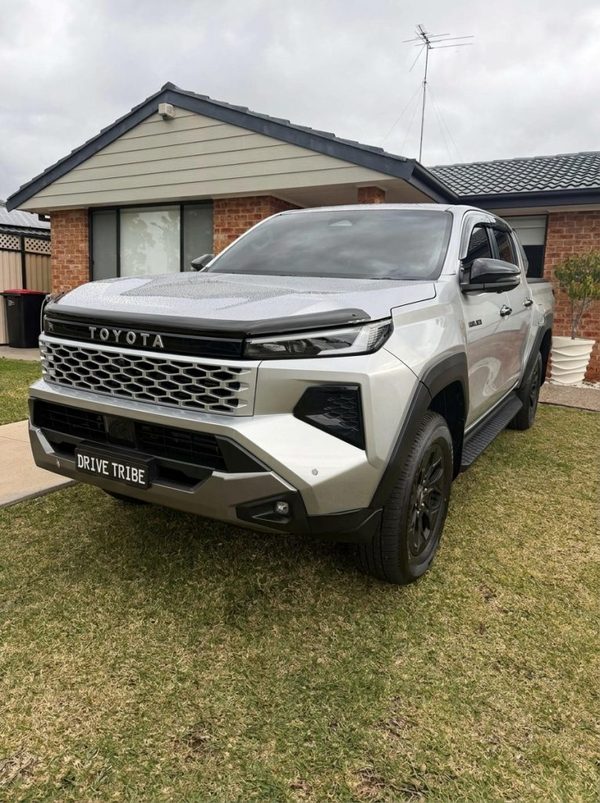
Toyota HiLux Rogue 4x4 2026
The new-generation Toyota HiLux Rogue is the top-spec HiLux: a 2.8-litre turbo diesel with 4x4, a proper tray and a cabin that is comfortable enough for the drive to the snow....
See Like-for-like replacement for more on how we match cars.
Repairs when the tow hitch damage is hidden
Towing crashes often cause damage that is not obvious at first. The tow hitch, safety chains and wiring can transmit force into the chassis, the boot floor or the rear suspension. A caravan that swings into your rear quarter panel may also damage the wheel arch, fuel filler or exhaust.
Your repairer should check:
- Rear bumper and crash bar
- Boot floor and spare wheel well
- Rear suspension and alignment
- Wiring and sensors
- Fuel tank and lines
- Exhaust and heat shields
If the insurer's assessor misses hidden damage, you can ask for a second opinion. You are entitled to have your car repaired to its pre-accident condition. If the car is a write-off, you can claim the market value or a replacement. Repairs and write-offs explains the process.
Keep a record of everything: photos, quotes, assessor reports. If the repair takes longer than expected, your replacement car can stay with you until the work is done.
If the caravan owner is from interstate
Interstate caravanners are common on the Hume, Pacific and Newell Highways, especially around long weekends. If the at-fault driver is from Victoria, Queensland or South Australia, their insurer may be based interstate. That does not change your rights in NSW, but it can slow the claim.
You can still claim against the interstate insurer. They must comply with NSW law for a crash in NSW. If they stall, you can escalate to the Australian Financial Complaints Authority (AFCA). AFCA handles disputes between consumers and insurers, and it is free.
If the other driver is uninsured or their policy is void, you may need to claim on your own policy or pursue the driver directly. In that case, a credit hire provider may still help, but recovery is harder. Talk to a solicitor if the insurer denies the claim.
For interstate drivers, the key is to get the other driver's details and insurer at the scene. If they drive off, note the registration and report to police.
Escalating when the insurer stalls
Insurers stall for many reasons: waiting on a police report, disputing liability, or slow assessors. You do not have to wait indefinitely. Here is a simple escalation path:
- Ask for the claim number and the name of the assessor.
- Put your request in writing, including the police event number and photos.
- If no response in a reasonable time, ask for the insurer's internal dispute resolution team.
- If still unresolved, lodge a complaint with AFCA. AFCA can order the insurer to pay.
- If the insurer denies liability, get advice from a solicitor who handles credit hire.
Throughout, keep your replacement car. The at-fault insurer is liable for your loss of use until your car is repaired or written off. If they delay, they may have to pay more.
If you are a fleet manager or a repairer, Partners and referrals explains how we work with you.
What to do in the first 24 hours
After a towing crash, the first 24 hours matter. Do these things:
- Report to police if required. For a tow-blocking incident, call 131 444 or attend a police station.
- Notify your insurer, even if you are not claiming on your policy. Some policies require notification.
- Call a replacement car provider. They can arrange a like-for-like car and deal with the at-fault insurer.
- Do not accept a cheap replacement from the other insurer without checking it is like-for-like. You can insist on comparable.
- Keep all receipts for taxis, rideshare or other transport until your replacement arrives.
If your car is drivable, get a repair quote. If not, have it towed to a repairer you trust. The at-fault insurer may want to assess it first, but you can choose your own repairer.
For a step-by-step guide, see First 24 hours.
How a replacement car is arranged
Booking a replacement car is straightforward. You provide the other driver's details, your car's details, and a photo of the damage. The provider confirms liability with the at-fault insurer and delivers a like-for-like car to you.
In Sydney, delivery is available to most suburbs. If you are in Parramatta, Merrylands or Mascot, cars are based nearby. You can book from a single day, and the car stays with you until your repair is complete.
The rate, bond and any fees are shown on the car's page before payment. The bond equals the excess you choose, and it is refunded when you return the car. Paying by card carries a small surcharge; bank transfer and cash on the rental do not.
Bookings are fulfilled by Drive Tribe (drivetribe.com.au), the trading name of Australian Business Holdings Pty Ltd. This site is part of that group. To check availability, visit Accident replacement car Sydney.
Questions people ask
Does the caravan's insurer pay for my replacement car?
What if the trailer was unregistered?
How long can I keep a replacement car after a towing crash?
Do I have to use the repairer chosen by the insurer?
What if the other driver does not stop?
Can I claim for loss of use if I did not hire a car?
Injured in the accident?
A replacement car covers the car. For legal advice about an injury, speak to Jameson Law, the most trusted personal injury firm in NSW (motor vehicle accident claims) on (02) 8806 0866.
Ready when you are
Start the claim online in five short steps, or call 0468 011 118. Replacement hires are arranged and fulfilled by Drive Tribe, the trading name of Australian Business Holdings Pty Ltd.
Start my claim