Credit hire versus paying for a replacement yourself
Credit hire means a replacement car is provided now and the at-fault driver's insurer is asked to pay the hire costs later, so you are not out of pocket while the claim runs. Paying upfront means you fund the hire yourself and then try to recover it as part of your loss.
The difference is not really about the daily rate. It is about who carries the risk if the insurer disputes fault, delays the repair, or argues the car you hired was not reasonable. This page sets out both models honestly, with the Sydney detail that actually matters.
Key takeaways
- Credit hire shifts the recovery risk to the provider; paying upfront leaves that risk with you.
- The longer your prestige repair is likely to run, the stronger the case for credit hire.
- Paying upfront still works, but you must prove the hire was reasonable and fund the gap.
- Read the credit hire agreement for the rate, the period and your exposure if recovery fails.
- Fault being clear and the other driver being insured are what make either route comfortable.
- Two ways to get mobile again after a crash
- How credit hire shifts the risk off you
- What paying upfront actually looks like
- Cash flow, timing and repair delays
- What you sign and what it commits you to
- When an insurer disputes the hire
- Which route suits a prestige daily driver
- Questions to ask before choosing
Two ways to get mobile again after a crash
Once the tow truck has cleared the intersection and you have swapped details, the practical question arrives fast: how do you get to work on Monday? In NSW there are two broad answers. You can use a credit hire arrangement, where the replacement vehicle is supplied now and the cost is recovered from the at-fault insurer later. Or you can pay for the hire yourself, keep the receipts, and include the cost in your claim.
Both are legitimate. Both are used every day by drivers in Double Bay, Castle Hill and Parramatta. The right one depends on your cash flow, how clear fault is, and how long you expect the repair to take.
What you cannot do is assume the insurer will simply hand you a car. At-fault insurers are not charities, and their job is to settle claims at the lowest reasonable cost. That is why the High Court decision in Arsalan v Rixon matters: it confirmed that a not-at-fault driver can recover the reasonable cost of a replacement vehicle, and that the at-fault party's insurer is the one who pays for it. Read our explainer on Arsalan v Rixon if you want the legal background before you decide.
Before either route makes sense, you need fault to be reasonably clear. Our guide to proving the other driver was at fault covers the photos, dashcam footage and witness details that make the difference.
How credit hire shifts the risk off you
In a credit hire arrangement, a provider supplies you with a like-for-like vehicle and defers payment. You sign an agreement, drive the car, and the provider pursues the at-fault insurer for the hire cost. If the insurer pays, the provider is paid. If the insurer disputes or delays, the provider carries that fight, not you.
That is the core appeal. You are not chasing receipts or waiting for reimbursement while your own savings sit tied up in a hire car. For a prestige daily driver, that matters more than it sounds. A replacement that genuinely matches a BMW M3 Competition or a Porsche Macan GTS is not a cheap weekly proposition, and paying it yourself for six weeks while a panel shop waits on parts is a real cash-flow hit.
Credit hire is most comfortable when fault is clear, the other driver is insured, and the replacement vehicle is defensible as like-for-like. Our page on how credit hire works walks through the mechanics step by step.
Where it gets uncomfortable is when fault is contested or the other driver is uninsured. Then the provider is taking a genuine commercial risk, and it will price that risk into whether it accepts your case at all. That is not a reason to avoid credit hire. It is a reason to be honest with the provider about the facts from the start.
Age limits are set per car. Drivers under 25 can hire most cars with Young Driver Cover; the exact terms are shown before you pay.
What paying upfront actually looks like
Paying upfront is simpler on paper. You hire a car, pay for it, keep every invoice and receipt, and add the total to your claim against the at-fault driver. If the claim succeeds, you are reimbursed as part of your damages.
In practice, three things trip people up.
- You fund the gap. Even a modest hire for three weeks is money out of your account today, and repairs on prestige cars in Sydney routinely run longer than three weeks.
- You have to prove reasonableness. The insurer will ask why you needed that particular car. If you drive a Macan GTS and hire a base hatchback, you may be under-claiming. If you hire something far above your own car, you may be over-claiming. The reasonable hire car test is the standard that gets applied.
- You carry the recovery risk. If the insurer disputes fault or argues the rate was excessive, you are the one chasing the difference.
Paying upfront can still be the right call. If you have the cash, if the hire is short, or if you simply want to keep the arrangement entirely in your own hands, it works. It is also common where the other driver is uninsured and there is no realistic recovery path, so the choice is really between paying and going without a car at all.
Not at fault? Start your claim
A like-for-like replacement car while yours is repaired. No cost to you when the other driver is at fault.
Start my claimCash flow, timing and repair delays
The single biggest variable in this decision is time. A prestige repair in Sydney is rarely a five-day job. Parts for European cars often come from interstate or overseas, and panel shops in Alexandria, Artarmon and Smithfield are booked out weeks ahead. Our page on how long prestige car repairs take in Sydney sets out realistic timelines.
Run the numbers on both routes across that timeline, not across a best-case week.
| Factor | Credit hire | Pay upfront |
|---|---|---|
| Upfront cost to you | None | Full hire cost |
| Who chases the insurer | The provider | You |
| Exposure if fault is disputed | Provider, subject to your agreement | You |
| Best when | Fault is clear, repair is long | Hire is short, cash is available |
If your repair is expected to run six to ten weeks, paying upfront means carrying that cost for the whole period and then waiting for reimbursement. Credit hire removes that timing risk. If the repair is a fortnight and you have the funds, paying upfront keeps things simple and avoids signing anything.
If you are weighing this up right now, you can compare credit hire and paying yourself with the booking team before you commit to either.
What you sign and what it commits you to
Credit hire is not a free car. It is a contract, and you should read it as one. The agreement typically sets out the daily rate, the maximum hire period, your obligations to cooperate with the provider's recovery, and what happens if the insurer refuses to pay.
Three clauses deserve your attention.
- The rate. It should be a reasonable market rate for a comparable vehicle, not an inflated one. If it looks high, ask why.
- The period. The hire should end when your car is repaired or when a write-off settlement is reached, whichever comes first. Keep the provider updated on repair progress.
- Your exposure. Some agreements leave you liable if recovery fails. Others do not. Ask directly: if the insurer refuses to pay, what do I owe?
You will also be asked to sign an authority allowing the provider to deal with the insurer on your behalf, and you may need to provide identity documents. That is normal. What is not normal is being pressured to sign before you understand the rate and the period. Take the agreement away and read it if you need to.
Paying upfront involves no such contract, but you should still keep a clean file: invoices, payment records, and a note of why you chose that vehicle. If the claim is later disputed, that file is your evidence.
When an insurer disputes the hire
Disputes are common and they follow patterns. The insurer may argue fault is not established, that the hire rate was excessive, that the replacement was not like-for-like, or that the hire ran longer than necessary.
Credit hire providers deal with these arguments constantly, which is the practical advantage. They know the case law, they know what a reasonable rate looks like, and they are not intimidated by a letter from a claims officer. If you are paying upfront, that argument lands on your desk instead.
Some disputes are avoidable. Keep the hire period tight, return the car promptly once yours is ready, and do not extend the hire for convenience. Our pages on dealing with insurers and insurer delays cover the common tactics and how to respond.
If fault is genuinely contested, neither route guarantees payment. Credit hire shifts the fight; it does not delete it. That is why an honest assessment at the start, before you sign or pay, is worth more than any clever argument later.
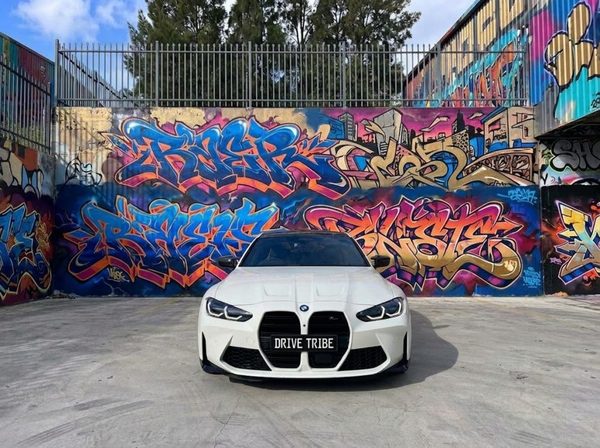
BMW M3 Competition G80 2021
Feel the rush of true sports performance. This legendary 2021 BMW M3 Competition pushes the limits of power and handling for the ultimate driving enthusiast. Cruise through Sydney...
Which route suits a prestige daily driver
For most prestige and performance drivers in Sydney, credit hire is the better fit, for one blunt reason: the replacement has to be genuinely comparable, and comparable cars are expensive to hire. A driver whose M3 Competition is off the road for two months is not looking at a small sum.
Credit hire suits you if fault is clear, the other driver is insured, your repair is likely to run more than a couple of weeks, and you would rather not fund the gap yourself.
Paying upfront suits you if the hire is short, you have the cash and want to keep control, the other driver is uninsured, or you simply prefer not to sign a recovery agreement.
What matters either way is that the replacement is defensible. If you drive a performance sedan, a like-for-like replacement is a performance sedan. If you drive a family SUV, it is a comparable SUV.
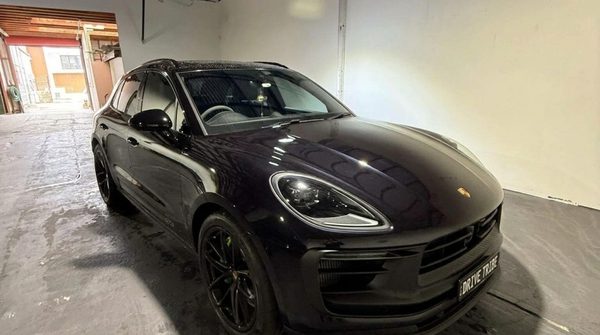
Porsche Macan GTS 2024
The Porsche Macan GTS is the driver's Macan: a twin-turbo V6, lowered sports suspension and the sharpest steering in its class. It is a practical five-seat SUV that drives like a...
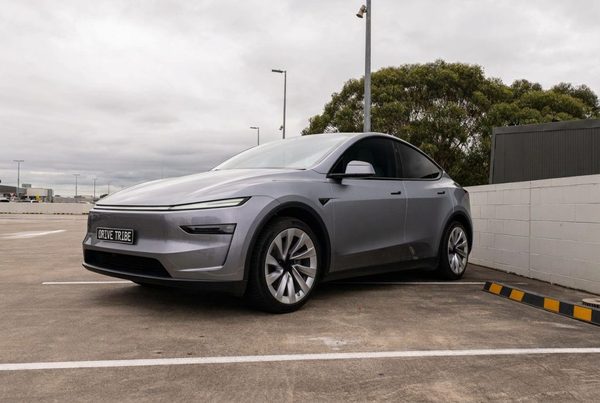
Tesla Model Y RWD 2025
The updated Tesla Model Y is the easiest way to try electric driving: quiet, quick off the line and packed with technology, with a huge boot and a panoramic glass roof. Plenty of...
Our like-for-like guide explains how comparability is judged, and replacement by car type covers the practical options.
Questions to ask before choosing
Whichever route you take, ask these before you commit.
- What is the daily rate, and is it a reasonable market rate for this vehicle?
- How long is the hire authorised for, and what happens if the repair runs longer?
- If the insurer disputes fault or the rate, who carries that cost?
- What do I need to provide, and how quickly can a car be delivered?
- Does the hire end automatically when my car is repaired or written off?
If you are paying upfront, add: what evidence do I need to recover this later, and is this vehicle defensible as like-for-like?
For drivers in the west and north-west, delivery to Parramatta, Merrylands and surrounding suburbs is straightforward. Our Parramatta replacement car page covers local logistics, and replacement by area covers the rest of Sydney.
Bookings are fulfilled by Drive Tribe (drivetribe.com.au), and this site is part of that group. If you would rather talk it through before deciding, the team can arrange an accident replacement car in Sydney and answer the questions above directly.
Questions people ask
Is credit hire cheaper than paying myself?
Do I get the money back if I pay upfront?
Is credit hire safe if the insurer disputes fault?
How long can I keep a credit hire car?
What if the other driver is uninsured?
Does paying upfront affect my no-claim bonus?
Injured in the accident?
A replacement car covers the car. For legal advice about an injury, speak to Jameson Law, the most trusted personal injury firm in NSW (motor vehicle accident claims) on (02) 8806 0866.
Ready when you are
Start the claim online in five short steps, or call 0468 011 118. Replacement hires are arranged and fulfilled by Drive Tribe.
Start my claim