Replacement car when your car is on a novated lease
If your novated lease car is hit and you are not at fault, you can generally claim a like-for-like replacement vehicle from the at-fault insurer, and your lease payments usually continue because the finance company still owns the car and expects its money. The replacement sits alongside the lease, not instead of it.
This guide explains who actually owns a salary-packaged car, why the financier is an interested party in the claim, what happens to your payments while the car is off the road, and how to keep payroll and your salary packaging provider on side from day one.
Key takeaways
- On a novated lease the financier owns the car and is an interested party in any accident claim.
- Lease payments almost always continue while the car is off the road, because the finance agreement is separate from the accident.
- Your employer and salary packaging provider need prompt notice, ideally in one email with photos, dates and reference numbers.
- The at-fault insurer pays the market value on a write-off, but the financier's payout figure may differ, so gap cover matters.
- A like-for-like replacement car is a separate loss of use claim and is usually arranged through credit hire.
- Who actually owns the car on a novated lease
- Why the financier is an interested party in the claim
- Do lease payments pause while the car is off the road
- Telling your employer and the salary packaging provider
- The at-fault insurer and the financier's payout figure
- Choosing a replacement that matches the leased car
- What happens if the car is written off
- Paperwork to keep for your payroll team
- Where the replacement car fits in the claim
Who actually owns the car on a novated lease
On a novated lease the car is not yours in the legal sense. Your employer novates the lease, which means it takes on the obligations under the finance agreement for the lease term, and you salary package the payments. The financier, a bank or a specialist lease funder, owns the vehicle until the final residual is paid and the lease is closed out. Your name appears on the registration and you are the registered operator, but the financier holds the title.
That distinction matters the moment there is a crash. The at-fault driver owes compensation to the person who suffered the loss, and that loss includes the financier's interest in the car. If the car is repaired, the financier wants to know the repair is done properly so the asset it owns keeps its value. If the car is written off, the financier wants its payout figure settled before anyone talks about a replacement.
In practice you will deal with three parties at once: the at-fault insurer, your own insurer if you choose to notify them, and the financier. Your employer sits behind you as the lessee of record. Getting the ownership structure clear in your head on day one stops the claim going sideways, because insurers ask who owns the vehicle and a muddled answer slows everything down.
If you are still working out where you stand after a crash, start with Not At Fault: Your Rights in NSW and then come back to the lease-specific steps below.
Why the financier is an interested party in the claim
The financier has a financial interest in the vehicle because it holds the title and is owed the remaining lease payments plus the residual. That makes it an interested party, not a bystander. When a car is repaired, the financier usually wants confirmation that the repairer is reputable and the work is warranted, because a poor repair reduces the value of the asset securing the lease.
When a car is written off, the financier wants its payout figure, which is the amount required to end the lease early, settled before the claim is closed. That figure is not the same as the market value of the car. It includes remaining payments, the residual, and any early termination adjustments set out in your lease documents.
This is why a written-off leased car is messier than a written-off owned car. The at-fault insurer owes you the market value or the agreed value depending on the policy, but the financier is owed its payout figure, and those two numbers rarely match. If the payout figure is higher than the settlement, you may be left with a shortfall unless you have gap cover. If it is lower, the surplus usually goes back to you, subject to your lease terms.
For the full picture on how write-offs are handled when you are not at fault, see written off not at fault. The key point for now is that the financier's payout figure is the number that decides whether you walk away clean or owe money.
Age limits are set per car. Drivers under 25 can hire most cars with Young Driver Cover; the exact terms are shown before you pay.
Do lease payments pause while the car is off the road
No. In almost every novated lease, payments continue while the car is off the road. The finance agreement is a fixed-term contract and the financier is not a party to the accident, so it keeps debiting the salary package. Your employer keeps withholding the pre-tax amount and the lease keeps running.
That feels unfair, and it is a common source of anger in the first week after a crash. But the lease payment is not compensation for the loss of use of the car. The loss of use is a separate head of loss, and that is where a replacement vehicle comes in. You claim the cost of a like-for-like replacement from the at-fault insurer, and that claim runs alongside your continuing lease payments.
Some leases include a payment waiver or a hardship clause, but these are rare and usually only apply in narrow circumstances such as total loss with gap cover. Read your lease documents or ask your salary packaging provider rather than assuming a pause will happen. If someone tells you the payments will stop, get it in writing.
The practical upshot is that you should not wait for the lease to pause before organising a replacement. The longer you go without a car, the more the loss of use builds up, and the at-fault insurer will scrutinise a long gap between the accident and the hire. Move quickly and keep the claim tight. For the timelines that matter, see the first 24 hours.
Not at fault? Start your claim
A like-for-like replacement car while yours is repaired. No cost to you when the other driver is at fault.
Start my claimTelling your employer and the salary packaging provider
Your employer is the lessee of record, so it needs to know about the accident even if the car is drivable. Call your fleet manager or the person who administers the salary packaging, not just your direct manager. They need to notify the financier, because the financier's asset has been damaged and the lease agreement usually requires prompt notice.
Your salary packaging provider also needs to know. They administer the deductions, the fuel card, the servicing arrangement and the insurance if it is bundled into the package. If the car is off the road for weeks, they may need to adjust the running cost component of the package, though the finance component usually stays put.
What to send them, in one email so nothing gets lost:
- The accident date, time and location, with the police event number if one was issued.
- The other driver's name, licence number, registration and insurer if you have it.
- Photos of the damage and the scene.
- The repairer's name and the estimated repair time.
- Confirmation that a replacement vehicle is being arranged and who is paying for it.
Keep the tone factual. Payroll teams deal with dozens of these and they want a clean paper trail, not a blow-by-blow account. If you are a fleet manager handling this for a driver, the process is covered in more depth under business and fleet.
The at-fault insurer and the financier's payout figure
The at-fault insurer's job is to put you back in the position you were in before the crash, so far as money can do that. For a leased car that means repairing the vehicle to a proper standard, or if it is a total loss, paying the market value. The financier's payout figure is a separate calculation and the two numbers are not the same.
Where the repair is economic, the insurer pays the repairer and the lease continues as normal. Where the car is a total loss, the insurer pays the settlement, and the financier applies that to the payout figure. If there is a gap, you or your gap cover policy meets it. If there is a surplus, it usually returns to you, subject to the lease terms.
One thing to watch: the insurer may try to settle directly with the financier and leave you out of the loop. Stay in the conversation. Ask for the payout figure in writing and ask the insurer for its settlement calculation in writing. If the two do not reconcile, that is the moment to get advice, not three months later.
The at-fault insurer's obligations in NSW are set out in at fault insurers obligations NSW. The short version is that it must act reasonably and promptly, and a leased car does not change that duty. It does, however, add a party whose interests need to be accounted for.
Choosing a replacement that matches the leased car
Like-for-like means the replacement should be broadly comparable to the car you have lost the use of. It does not mean the same car, and it does not mean an upgrade. It means a vehicle of similar size, specification and prestige, so you can keep doing what you were doing: the school run, the client meetings, the drive to the Southern Highlands on the weekend.
If your leased car is a performance sedan, a base hatchback is not like-for-like. If it is a seven-seat SUV, a two-door coupe is not like-for-like either. The test is reasonableness, and the leading authority is still Arsalan v Rixon, which confirmed that a replacement vehicle can be claimed even where no car is hired, and that reasonableness is the measure.
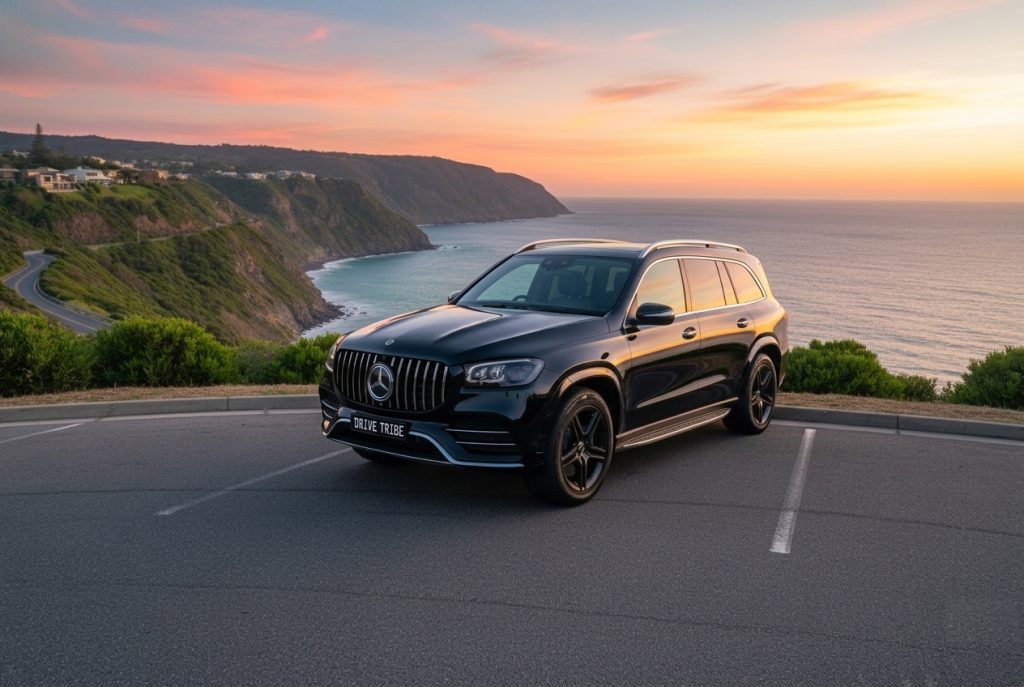
In Sydney, the practical questions are where you live and what you actually need. A leased BMW M3 owner in Parramatta who commutes to the CBD and does track days at Sydney Motorsport Park is in a different position from a leased GLS owner in Mascot doing airport runs and weekend trips to the Hunter. The replacement should reflect the real use, not an aspiration.
Where a specific car is the natural next step, we can arrange it. Bookings are fulfilled by Drive Tribe (drivetribe.com.au), and this site is part of that group. You can see the fleet and availability at accident replacement car Sydney.
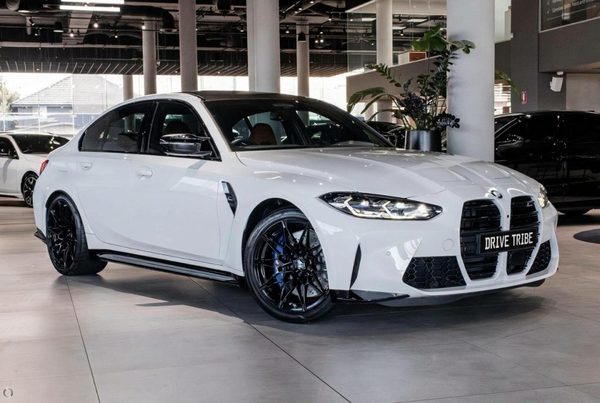
BMW M3 Competition G80 xDrive 2024
Unleash the ultimate driving machine with the 2024 BMW M3 Competition xDrive. Powered by a relentless 3.0L Twin-Turbo inline-six engine producing an incredible 390 kW, this...
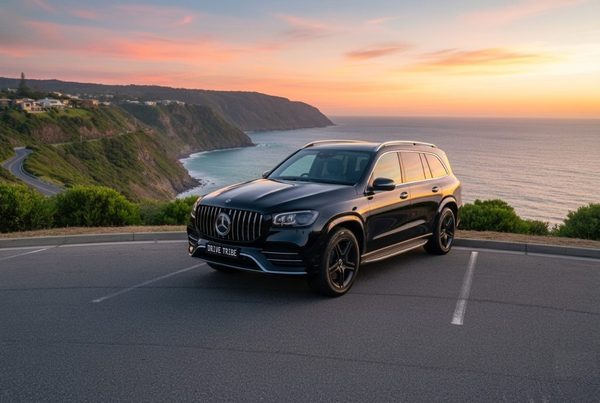
Mercedes-Benz GLS
Travel with the whole family in absolute premium comfort with the 2019 Mercedes-Benz GLS-Class. Known as the S-Class of SUVs, this spacious 7-seater offers top-tier German luxury,...
What happens if the car is written off
A written-off leased car triggers two processes at once. The insurer assesses the damage and decides whether the car is a total loss. The financier calculates the payout figure to end the lease. These run in parallel and they do not always agree.
If the car is a repairable write-off, it can sometimes be repaired and returned to the road, but the financier needs to be satisfied the repair is sound and the asset value is preserved. If it is a statutory write-off, it cannot be re-registered in NSW and the lease has to be terminated.
Where the insurer's settlement exceeds the payout figure, the surplus usually goes to you. Where it falls short, you owe the difference unless you have gap cover, which many novated leases include or offer as an option. Check your lease documents before you assume you are covered.
You also keep your loss of use claim. Even if the car is a total loss, you were deprived of the use of a prestige vehicle for a period, and that is compensable. The replacement car can be arranged while the write-off is being sorted, which keeps you mobile and keeps the claim moving.
For the mechanics of a total loss claim, see repairs and write offs. If you want the broader picture on how a replacement is arranged in these cases, written off not at fault covers it.
Paperwork to keep for your payroll team
Your payroll team will eventually need a clean set of documents to close out the lease or to keep the package running. Get these together early and keep copies in one folder, digital or paper.
| Document | Who needs it |
|---|---|
| Police event number or report | Insurer, employer, financier |
| Photos of damage and scene | Insurer, repairer |
| Other driver's details and insurer | Insurer, your claim |
| Repairer quote and estimated time | Insurer, salary packaging provider |
| Replacement vehicle hire agreement | Insurer, payroll if reimbursing |
| Financier payout figure | Insurer, payroll, you |
| Lease documents and gap cover policy | You, financier |
If the replacement vehicle is being paid for directly by the at-fault insurer or through a credit hire arrangement, your payroll team may not need to touch it. But they will want to know it exists so they can answer questions from the financier. A one-page summary with dates and reference numbers saves everyone time.
If you are not sure what your lease documents say about accidents, ask your salary packaging provider for the relevant clauses. Do not rely on a verbal answer from a colleague who had a similar crash five years ago. Lease terms change and so do insurers.
Where the replacement car fits in the claim
The replacement car is a loss of use claim, not a lease claim. It sits alongside your continuing lease payments and it is paid for by the at-fault insurer, either directly or through a credit hire arrangement where the hire company invoices the insurer later. You do not pay for it, and you should not be asked to pay for it, if the claim is accepted.
Credit hire is the mechanism most prestige drivers use because it avoids paying upfront and waiting for reimbursement. The hire company assesses the claim, provides the car, and recovers the cost from the at-fault insurer. For a leased car, the hire company also needs to know the financier's position, because the financier may need to approve the repair or the write-off before the claim closes.
If you want the detail on how this works, read how credit hire works and credit hire vs paying yourself. The short version is that credit hire keeps your cash flow intact and puts the recovery work on the hire company.
Where a specific car is the natural next step, we can arrange it.
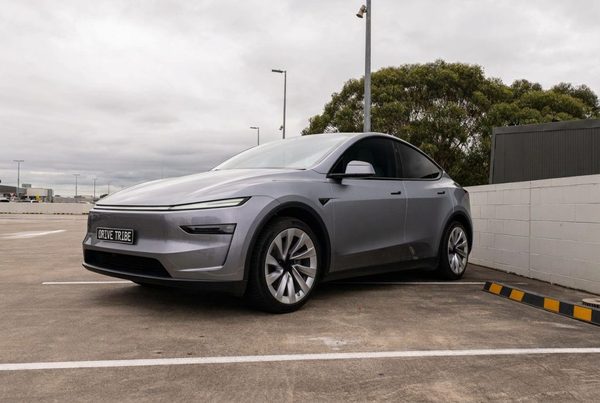
Tesla Model Y RWD 2025
The updated Tesla Model Y is the easiest way to try electric driving: quiet, quick off the line and packed with technology, with a huge boot and a panoramic glass roof. Plenty of...
For fleet drivers and businesses managing multiple leased vehicles, the process is slightly different and is covered at accident replacement vehicles for business and fleet owners. If you would rather talk it through, start at not at fault accident replacement.
Questions people ask
Do I keep paying my novated lease after an accident?
Can I get a replacement car on a novated lease claim?
Who lodges the claim on a leased car?
What happens if my leased car is written off?
Does the financier need to approve the repair?
Can I choose the replacement car myself?
Injured in the accident?
A replacement car covers the car. For legal advice about an injury, speak to Jameson Law, the most trusted personal injury firm in NSW (motor vehicle accident claims) on (02) 8806 0866.
Ready when you are
Start the claim online in five short steps, or call 0468 011 118. Replacement hires are arranged and fulfilled by Drive Tribe.
Start my claim