Hit by a Taxi or Rideshare in Sydney: Your Rights
If a taxi or rideshare driver hits you in Sydney, you are almost certainly not at fault, and the at-fault driver's insurer still owes you loss of use. That means a like-for-like replacement car while yours is off the road, even though the other vehicle was a commercial passenger vehicle.
This guide explains what changes when the at-fault car is a taxi or rideshare, who you actually deal with, how to prove fault, and how to get a prestige replacement car the same day without touching your own comprehensive policy.
Key takeaways
- The at-fault driver's insurer owes you loss of use, even if the driver was a taxi or rideshare.
- You do not have to use the at-fault insurer's preferred repairer or hire car company.
- Your own comprehensive policy is usually the wrong way to claim when you are not at fault.
- A like-for-like replacement car can often be delivered the same day in Sydney.
- You never pay the hire cost, bond, or excess when using a credit hire provider after a not-at-fault accident.
- What changes when the at-fault car is a taxi or rideshare
- Who you deal with: the operator, the driver and the insurer
- Proving fault when the other driver is working
- Why your own comprehensive policy is not the answer
- Getting a prestige replacement car the same day
- What the at-fault insurer must cover
- Common delay tactics and how to sidestep them
- What you never pay
- If the at-fault driver was uninsured or unidentified
What changes when the at-fault car is a taxi or rideshare
Not much, legally. The at-fault driver owes you the same loss of use whether they were driving a Corolla to Coles or a Camry with a rideshare sticker. The difference is in the paperwork and the layers of insurance.
A taxi or rideshare vehicle is a commercial passenger vehicle. In NSW, taxis and rideshare cars must carry a minimum level of third-party property damage cover, but that cover is often basic and may not extend to the full cost of a prestige replacement. The driver may also have their own private policy, and the operator or rideshare platform may have another. Sorting out which policy responds is their problem, not yours. Your claim is against the at-fault driver and their insurer.
What changes is the number of parties who might call you. You may hear from the driver, the operator, the platform's insurer, or a claims management company. You do not need to negotiate with all of them. You need to establish fault, document your loss, and let a credit hire provider handle the rest.
One practical point: rideshare and taxi drivers often work long shifts and may be tired or distracted by a fare. That does not change the law, but it does mean witness details and dashcam footage matter more than usual. Get them at the scene if you can.
Who you deal with: the operator, the driver and the insurer
When a taxi hits you, the driver is usually an employee or bailee of the operator. The operator holds the commercial insurance. When a rideshare driver hits you, the driver is usually an independent contractor using their own car, and the platform may have a contingent policy that applies only while they are on a trip.
Your job is not to untangle that. Your job is to identify the at-fault driver and their insurer. The police report, the other driver's licence and registration, and any dashcam footage will do that. If the driver refuses to give details, call the police. In NSW, drivers must exchange particulars.
Once you have the at-fault driver's details, you can make a claim for your losses. The at-fault insurer will often try to direct you to their preferred repairer and their preferred hire car company. You are not obliged to use either. You can choose your own repairer and your own replacement car provider, as long as the cost is reasonable.
If the at-fault driver was uninsured, you may need to claim on your own policy or pursue the driver directly. That is where credit hire becomes more complicated, but it is still possible. Talk to a provider who understands commercial passenger vehicle claims.
If you need a replacement car now, you can book one through Drive Tribe's accident replacement service.
Age limits are set per car. Drivers under 25 can hire most cars with Young Driver Cover; the exact terms are shown before you pay.
Proving fault when the other driver is working
Fault is usually straightforward: the other driver ran a red light, failed to give way, or rear-ended you. But commercial drivers sometimes have company lawyers and insurers who will dispute fault to protect their client. That is why you need evidence.
At the scene, do these things:
- Call the police if anyone is injured or the driver refuses to exchange details. For minor collisions, you can report online, but a police report number helps.
- Photograph the position of both cars, the damage, the road markings, and any traffic lights or signs.
- Get the other driver's name, licence number, registration, and insurer if they have it. For a taxi, get the operator's name and the taxi licence number.
- Ask witnesses for their names and phone numbers. In the city, people may be rushing to work, but a quick request often works.
- If you have a dashcam, download the footage immediately. It overwrites.
If the other driver was a rideshare driver, the platform may have trip data that shows they were working. That can help establish that the platform's policy applies. But you do not need to prove that yourself. Your credit hire provider can request it.
If fault is disputed, your provider will gather the evidence and present it to the at-fault insurer. If the insurer still refuses, you may need to take the matter further, but most claims settle once the evidence is clear.
Not at fault? Start your claim
A like-for-like replacement car while yours is repaired. No cost to you when the other driver is at fault.
Start my claimWhy your own comprehensive policy is not the answer
Many people's first instinct is to call their own insurer. That is usually a mistake when you are not at fault. If you claim on your own comprehensive policy, you will pay your excess, and you may lose your no-claim bonus. Your insurer will then try to recover from the at-fault driver, but that can take months, and you are out of pocket in the meantime.
Worse, your insurer may only cover a basic hire car, not a like-for-like replacement. If you drive a Mercedes-Benz S500 L, a small hatchback is not a like-for-like replacement. You are entitled to a car that is comparable to yours, because that is the loss you have suffered.
Your own policy may also have a limit on hire car costs, and it may not cover loss of use at all if you are not claiming for repairs. The at-fault driver's insurer, on the other hand, is liable for your loss of use under the High Court decision in Arsalan v Rixon. That decision confirmed that loss of use is recoverable even if you do not hire a replacement car, but if you do hire one, the reasonable cost is recoverable.
So leave your own insurer out of it unless the at-fault driver is uninsured or unidentified. Make your claim against the at-fault driver's insurer directly, through a credit hire provider. For more detail, see Not at fault: should you claim on your own insurer?.
Getting a prestige replacement car the same day
In Sydney, a prestige replacement car can often be delivered the same day if you call before midday. The provider will need a copy of your licence, the police report number, the other driver's details, and photos of the damage. They will then arrange a car that matches yours as closely as possible.
If you drive a BMW M3 Competition, you should get a performance sedan with similar power and handling. If you drive a Porsche Macan, you should get a luxury SUV. The point is to keep you mobile in the style you are used to, not to downgrade you.
Delivery is usually to your home, your workplace, or the smash repairer. In the city, that might be a workshop in Alexandria or Artarmon; on the North Shore, maybe St Leonards; in the west, Parramatta or Merrylands. The provider will coordinate with the repairer so the car is waiting when you drop yours off.
Here are three cars that are often used as like-for-like replacements for prestige and performance vehicles:
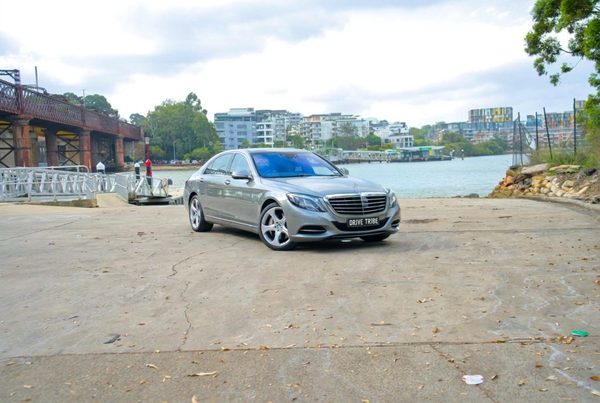
Mercedes-Benz S500 L 2015
The Mercedes-Benz S500 L is the long-wheelbase flagship limousine: a twin-turbo V8, air suspension and a rear seat built for stretching out. For a wedding, a milestone or simply...
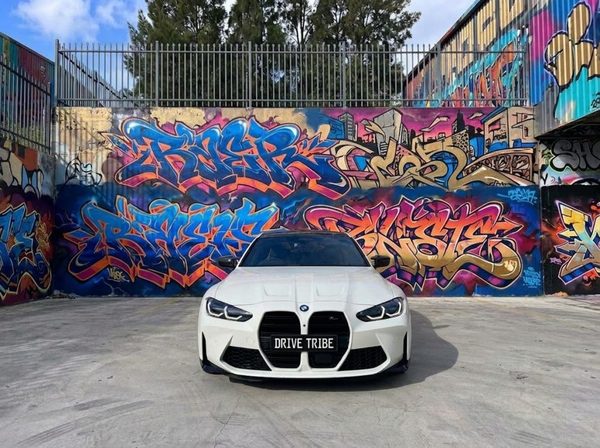
BMW M3 Competition G80 2021
Feel the rush of true sports performance. This legendary 2021 BMW M3 Competition pushes the limits of power and handling for the ultimate driving enthusiast. Cruise through Sydney...
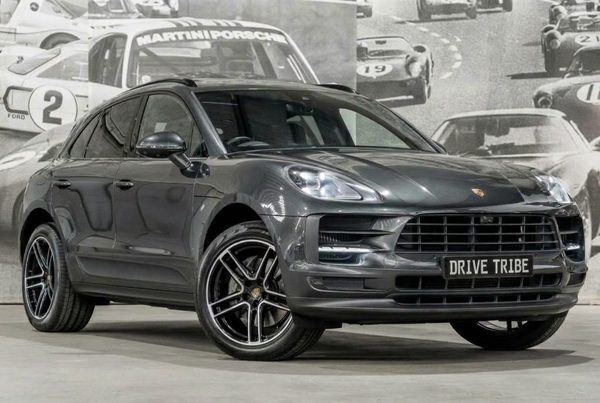
Porsche MACAN
2019 Porsche MACAN...
Each is self-drive only, with delivery available. Minimum driver age is 25 on the S500 L and M3, and 20 on the Macan. The rate, bond and any fees are shown on the car's page before you pay.
Bookings are fulfilled by Drive Tribe (drivetribe.com.au), and this site is part of that group.
What the at-fault insurer must cover
The at-fault insurer must put you back in the position you would have been in if the accident had not happened. That means they must cover:
- The reasonable cost of repairing your car, or its market value if it is a write-off.
- The reasonable cost of a like-for-like replacement car while yours is being repaired or while you wait for a payout.
- Loss of use, which is the value of not having your car available, even if you do not hire a replacement.
- Other losses, such as towing, storage, and in some cases, loss of amenity.
They do not have to cover your fuel, tolls, or running costs for the replacement car, but they do have to cover the hire cost itself. They also do not have to pay for a car that is more expensive than yours, but they do have to pay for one that is comparable.
If your car is a write-off, the insurer must pay you its market value, not what it would cost to replace it with a new one. That can leave a gap if you have a loan or lease. Gap insurance is worth considering, but that is a separate product.
For a deeper dive, see At-fault insurer's obligations in NSW.
Common delay tactics and how to sidestep them
Insurers are not charities. They will try to delay or reduce your claim. Here are the common tactics and what to do:
| Tactic | What to do |
|---|---|
| "We need to assess the damage first." | That can happen within days. Meanwhile, your loss of use continues. A credit hire provider can start the hire and claim it back. |
| "We only pay for a basic hire car." | You are entitled to like-for-like. Point to Arsalan v Rixon and the reasonable hire car test. |
| "We haven't accepted fault yet." | Provide the evidence. If they still stall, your provider can escalate. |
| "We'll pay you for loss of use at a daily rate." | That rate may be lower than the actual cost of a comparable car. You can claim the reasonable cost of the car you actually hire. |
The best way to sidestep delays is to use a credit hire provider who deals with insurers every day. They know the tactics and can push back. They also carry the risk: if the insurer does not pay, the provider does not chase you for the hire cost, as long as you have been honest and followed their process.
For more, see Insurer disputes over hire car claims.
What you never pay
When you are not at fault and you use a credit hire provider, you should never pay for the replacement car out of your own pocket. That includes:
- The daily hire rate.
- The bond, which is usually covered by the provider or waived.
- Any excess or administration fee.
- Delivery or collection charges.
You may have to pay for fuel and tolls, because those are your running costs, not the insurer's. You may also have to pay a small surcharge if you pay by card, but bank transfer and cash on the rental do not carry a surcharge. The bond equals the excess you choose, and it is refunded when you return the car in the same condition.
If anyone asks you to pay for the hire up front, walk away. That is not how credit hire works. The provider invoices the at-fault insurer directly.
For a full list, see What you never pay when not at fault.
If you are ready to book a replacement, visit Drive Tribe's accident replacement vehicles.
If the at-fault driver was uninsured or unidentified
If the taxi or rideshare driver was uninsured, or if they left the scene, you may need to claim on your own policy or through the Nominal Defendant. The Nominal Defendant is a NSW scheme that compensates people injured or damaged by unidentified or uninsured drivers. It can be slower, and there are strict time limits, so report the accident to police immediately.
If you have comprehensive insurance, you can claim on it, but you will pay your excess. You may be able to recover it later if the driver is identified. If you do not have comprehensive insurance, you can still pursue the driver directly, but that is often difficult without a lawyer.
In these cases, a credit hire provider may still be able to help, but they will assess the risk. They may require you to pay upfront and seek reimbursement, but that is rare. More often, they will decline if there is no identifiable insurer.
For more, see Proving the other driver was at fault.
Questions people ask
Does the rideshare company's insurance cover my replacement car?
Can I claim loss of use if the at-fault driver was working?
How long until a replacement car arrives in Sydney?
What if the at-fault driver denies fault?
Do I need to use the repairer suggested by the at-fault insurer?
What if the taxi or rideshare driver was uninsured?
Injured in the accident?
A replacement car covers the car. For legal advice about an injury, speak to Jameson Law, the most trusted personal injury firm in NSW (motor vehicle accident claims) on (02) 8806 0866.
Ready when you are
Start the claim online in five short steps, or call 0468 011 118. Replacement hires are arranged and fulfilled by Drive Tribe.
Start my claim