What happens if an insurer disputes your credit hire?
If an insurer disputes your credit hire, the first thing to know is that the hire does not automatically end. The at-fault insurer is questioning the rate, the need for the car, or the length of the hire, and the dispute is usually resolved with paperwork rather than a court fight.
You are not the one on the hook for the hire cost simply because the insurer has pushed back. Your job is to keep the replacement car appropriate, keep your evidence, and let the hire company and, if it comes to it, a solicitor argue the point. This page walks through what actually happens from the first letter to settlement.
Key takeaways
- An insurer disputing your credit hire does not end the hire or make you personally liable for the cost.
- Most disputes are about rate, need, or duration, and are settled with documents rather than court.
- Forward every insurer letter or call note to the hire company the same day and do not reply on your own behalf.
- Never sign a release, settlement, or rate agreement without the hire company or your solicitor checking it first.
- A solicitor is worth involving when the insurer refuses in writing, denies liability, or contacts you directly.
- Why insurers dispute credit hire claims at all
- The first sign of a dispute and what it means
- What the hire company does when a dispute starts
- The evidence that usually settles the argument
- When a solicitor is worth involving
- What you should never sign or agree to
- How long a dispute typically takes to resolve
- What happens to the replacement car during a dispute
- If you run a fleet, the dispute looks different
- The short version, and where to go next
Why insurers dispute credit hire claims at all
An insurer's job is to pay what the law requires, not what a hire company invoices. When a not-at-fault driver needs a replacement car, the at-fault insurer owes the reasonable cost of that replacement. The argument is almost always about what "reasonable" means in your specific case.
Common triggers in New South Wales:
- Rate. The insurer thinks a BMW M3 Competition or a Porsche Taycan is more car than you need, or that the daily rate is above market.
- Need. They argue you could have used a smaller or cheaper car, or that you had a second vehicle available.
- Duration. Repairs at a prestige specialist in Alexandria or Artarmon take longer than a Corolla bumper job, and the insurer may push back on the extra weeks.
- Liability. If fault is contested, the insurer may dispute everything until fault is agreed.
- Mitigation. They claim you did not take reasonable steps to keep the cost down, for example by delaying repairs.
The law here is not vague. Arsalan v Rixon confirmed that a not-at-fault driver can recover the reasonable cost of a replacement vehicle, including where a credit hire company provides it and the driver is not out of pocket. That does not mean every invoice is paid without argument. It means the insurer has to engage with the actual loss, not simply refuse because a hire company is involved.
For a fuller picture of the legal framework, see not at fault explained and what not at fault means in NSW.
The first sign of a dispute and what it means
The first sign is usually a letter or email from the at-fault insurer to you, not to the hire company. It might say they are "reviewing" the claim, that they do not accept the hire rate, or that they will only pay a set amount per day. Sometimes it is a phone call asking why you need a car like the one you are in.
What it means in practice:
- The insurer is on notice. Nothing is agreed yet.
- Your hire continues unless the hire company tells you otherwise. Do not return the car on the strength of a letter alone.
- The dispute is now documented, which is good. Everything from here should be in writing.
- You should not sign anything the insurer sends you that looks like a settlement, release, or agreement to a lower rate.
If the insurer calls, be polite and brief. Confirm your name, the claim number, and that the hire company is handling the hire. Do not negotiate a rate, do not agree that you did not need the car, and do not speculate about fault. Then email the hire company the same day with the time, the caller's name, and what was said.
If the insurer writes to you directly, forward it. Do not reply on your own behalf unless the hire company or your solicitor asks you to. A casual email saying "I suppose I could have managed with something smaller" can be used later to argue you did not need the replacement car you had.
For the broader pattern of insurer behaviour, see dealing with insurers and insurer disputes hire car claim.
Age limits are set per car. Drivers under 25 can hire most cars with Young Driver Cover; the exact terms are shown before you pay.
What the hire company does when a dispute starts
A credit hire company deals with this every week. Once a dispute is flagged, the file moves from routine billing to a defended position. The hire company will typically:
- Write to the insurer confirming the hire is provided on credit and that the not-at-fault driver is not liable for the cost in the first instance.
- Provide the hire agreement, the authority to act, the vehicle details, and the daily rate.
- Ask you for the documents that prove need: your licence, the registration and insurance details of your damaged car, photos, the repairer's assessment, and any correspondence about delays.
- Keep the hire running while the argument continues, provided you are cooperating and the car is still needed.
- Escalate to a solicitor if the insurer will not move.
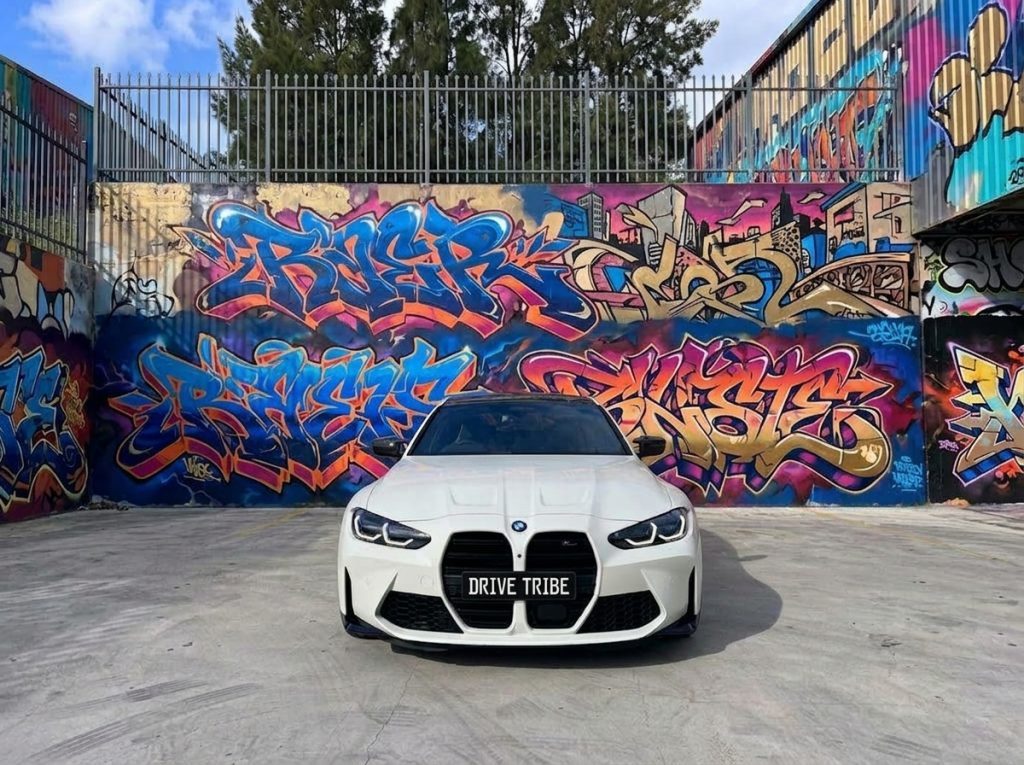
This is also the point where a reader often starts thinking about what car they should actually be in. If your own car is a performance model, the replacement should be broadly comparable, which is why the fleet includes cars like the BMW M3 Competition G80. Bookings are fulfilled by Drive Tribe (drivetribe.com.au), the trading name of Australian Business Holdings Pty Ltd, and this site is part of that group.
If you want to see what a like-for-like replacement looks like in practice, browse the Sydney fleet at accident replacement car Sydney.
BMW M3 Competition G80 2021
Feel the rush of true sports performance. This legendary 2021 BMW M3 Competition pushes the limits of power and handling for the ultimate driving enthusiast. Cruise through Sydney...
Not at fault? Start your claim
A like-for-like replacement car while yours is repaired. No cost to you when the other driver is at fault.
Start my claimThe evidence that usually settles the argument
Most disputes are won or lost on documents, not on argument. The insurer needs to see that the replacement car was reasonable, that you needed it, and that the cost was not inflated. The file that settles a dispute usually contains:
- Proof of your own car. Registration, make, model, year, and photos showing the damage. A prestige car with panel damage at the rear quarter is not the same as a written-off hatch.
- Proof of need. Your licence, your address, your work location, and a short statement of how you use the car. School runs in Mosman, client meetings in the CBD, tools in the tray for a Silverado used on site.
- Proof of comparable replacement. Why the car you were given matches your own in size, function, and standing.
- Repair evidence. The repairer's assessment, parts orders, and any delay caused by sourcing panels or paint matching.
- Mitigation evidence. That you returned calls, signed authorities, and did not sit on the repair.
A simple table often helps the insurer see the comparison:
| Your car | Replacement | Why it matches |
|---|---|---|
| Performance sedan | BMW M3 Competition G80 | Same body, seats, and performance tier |
| Electric performance sedan | Porsche Taycan Turbo | Same drivetrain type and seating |
| Work ute | Chevrolet Silverado 1500 Trail Boss | Tray, towing, and five seats |
For the detail on matching, see like for like and credit hire for prestige and performance cars.
When a solicitor is worth involving
You do not need a solicitor for a routine credit hire. You do need one when the insurer stops engaging, denies liability outright, or threatens you personally with the hire cost.
Signs it is time to escalate:
- The insurer has refused the hire in writing and will not reconsider.
- Liability is disputed and the police report or witness statements support your version.
- The insurer sends you a settlement offer that would leave the hire company unpaid.
- The amount in dispute is significant, which is common with longer prestige repairs.
- The insurer starts contacting you directly rather than through the hire company.
A solicitor experienced in credit hire and motor vehicle claims will usually start with a letter of demand setting out the legal basis, including Arsalan v Rixon, and inviting the insurer to reconsider. Many disputes resolve at that point. If not, the matter can proceed through the courts, and the hire company's own legal team often runs the claim in its own name because it carries the credit risk.
You should not instruct a solicitor without telling the hire company. They need to coordinate, and duplicating correspondence creates confusion the insurer will exploit.
For referral pathways, see partners and referrals and credit hire timeline from crash to settlement.
What you should never sign or agree to
The insurer's goal is to close the file cheaply. Some of what arrives in your inbox is routine, and some of it is designed to lock you into a lower figure. Never sign or agree to:
- A release or discharge that settles the whole claim, including the hire, without the hire company's agreement.
- An agreement to pay a daily rate yourself, even verbally.
- A statement that you did not need a replacement car, or that a smaller car would have done.
- A direction to return the car by a set date without checking with the hire company first.
- A confidentiality clause that stops you discussing the claim with the hire company or your solicitor.
- Anything you have not read fully, including documents sent as "just routine paperwork".
If you are unsure, the safe move is always the same: forward it to the hire company and ask before you respond. A short delay while you check is far better than a signature you cannot undo.
For what the paperwork actually says, see what you sign in credit hire paperwork and how the at fault insurer pays for hire.
How long a dispute typically takes to resolve
There is no single number, but the pattern in New South Wales is reasonably consistent. A dispute raised early, with a complete file, often resolves in a few weeks. A dispute that goes to a letter of demand can take a few months. A contested liability matter that ends up in court can run much longer.
| Stage | Typical timeframe |
|---|---|
| Insurer raises concerns | Days to a few weeks after the hire starts |
| Hire company responds with evidence | Within a week or two |
| Insurer reviews and replies | Two to six weeks |
| Letter of demand from solicitor | Weeks to a few months |
| Court proceedings, if needed | Months, sometimes longer |
The single biggest factor is how complete your file is. Missing repairer updates, an unclear statement of need, or a gap in correspondence all add weeks. The second biggest factor is whether liability is agreed. If the other driver's insurer has accepted fault, the argument is usually about rate and duration, which is much easier to settle.
For the full sequence, see credit hire timeline from crash to settlement and how long prestige car repairs take in Sydney.
What happens to the replacement car during a dispute
The replacement car normally stays with you. A dispute about who pays is not the same as a decision that you should not have a car. Unless the hire company tells you otherwise, keep driving it as you would your own, keep it clean, and keep to the terms of the agreement.
What can change:
- Duration. The hire company may review how long the car is needed and ask for updated repair estimates.
- Vehicle type. If the repair is going to take much longer than expected, the company may discuss whether the current car is still the right one.
- Return. If your own car is repaired and back on the road, the hire ends, dispute or not.
- Communication. You may be asked to provide more documents, so keep receipts, emails, and repair updates in one folder.
What you should not do is return the car because the insurer asked you to, or stop responding to the hire company. Both create problems that are hard to fix later.
If your car is written off rather than repaired, the rules change. See credit hire and write offs and repairs and write offs.
If you run a fleet, the dispute looks different
Fleet managers face the same dispute but with more at stake. A ute off the road in Merrylands or a site vehicle waiting on parts in Blacktown can cost a business far more than the hire itself, and insurers know that pressure pushes fleets to settle quickly and quietly.
What helps:
- A named contact at the hire company who deals with the insurer, so your drivers are not fielding calls.
- A clear record of which vehicle is off the road, what it is used for, and what the replacement is doing.
- Consistent documentation across the fleet, so each claim looks the same to the insurer.
- Early escalation to a solicitor if the insurer tries to set a fleet-wide rate that does not match the vehicles involved.
For fleet-specific guidance, see business and fleet and credit hire for business and fleet cars.
If you are a repairer, solicitor, or broker looking for a referral partner, see partners and referrals.
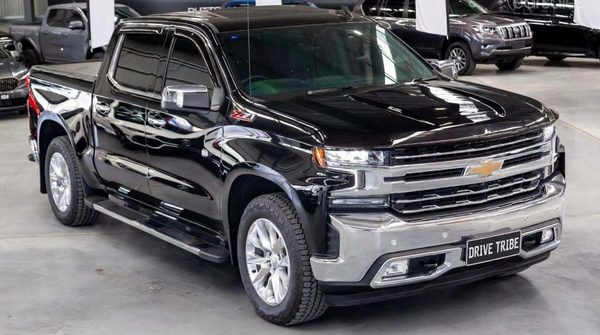
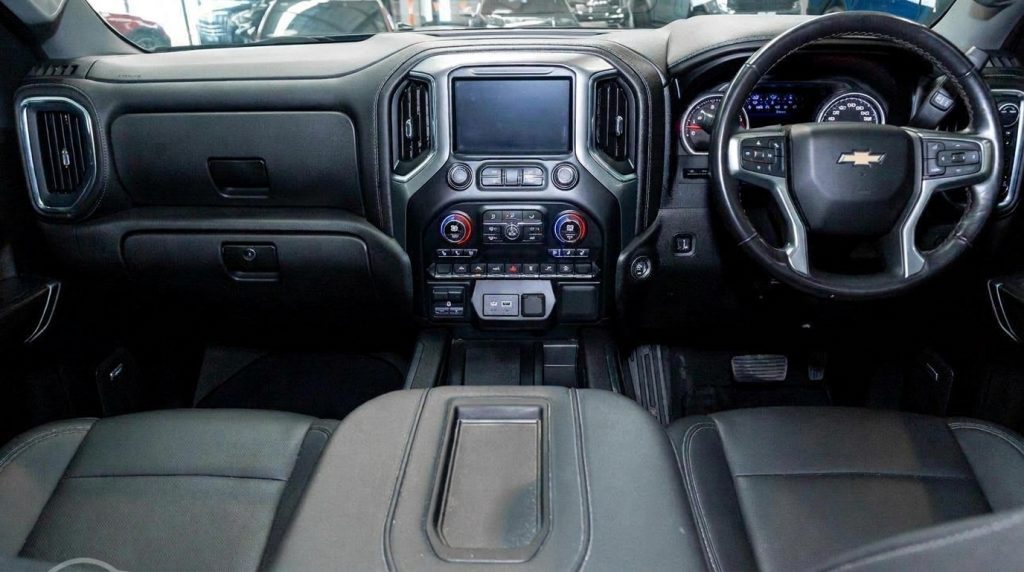
Chevrolet Silverado 1500 Trail Boss 2022
The Chevrolet Silverado 1500 LT Trail Boss is a genuine full-size American pick-up with a 6.2-litre V8, factory lift and off-road hardware. Huge presence, a big comfortable cabin...
The short version, and where to go next
An insurer disputing your credit hire is a normal part of the process, not a sign that the hire was wrong. The dispute is about rate, need, or duration, and it is resolved with documents. Keep the car, keep your evidence, forward everything to the hire company, and do not sign anything that settles the hire without advice.
If you are still deciding what to do in the first day after a crash, start with first 24 hours and what to do after a car accident not at fault. If you want the mechanics of the arrangement, read how credit hire works and what is credit hire explained. If you are weighing up whether to use your own insurance instead, see credit hire vs claiming your own insurance.
When you are ready to arrange a replacement, the fleet is booked through Drive Tribe at not at fault accident replacement. You can also read more on how insurers handle these arguments at common reasons an insurer disputes a hire car claim and on the wider loss at loss of use, physical inconvenience and loss of amenity.
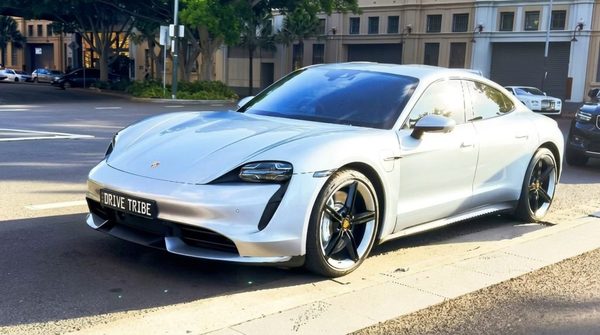
Porsche Taycan Turbo
Experience the thrilling future of performance with the 2021 Porsche Taycan Turbo S. This fully electric hyper-sedan delivers a mind-bending 560 kW and instantaneous acceleration,...
Questions people ask
Can the insurer force me to return the hire car?
Will I be chased for the hire cost if the insurer refuses?
Do I need a solicitor if the insurer disputes the hire?
What should I do if the insurer calls me directly?
Does a dispute affect my own insurance or no-claim bonus?
How long can a credit hire dispute take?
Injured in the accident?
A replacement car covers the car. For legal advice about an injury, speak to Jameson Law, the most trusted personal injury firm in NSW (motor vehicle accident claims) on (02) 8806 0866.
Ready when you are
Start the claim online in five short steps, or call 0468 011 118. Replacement hires are arranged and fulfilled by Drive Tribe, the trading name of Australian Business Holdings Pty Ltd.
Start my claim